By Zach Brown, Senior Mortgage Loan Officer, NMLS #2156538 ·
Updated August 6, 2026 · Columbia & Boone County, Missouri
The short answer
Most Columbia buyers qualify for a home priced around 3 to 4 times their gross annual income, depending on debt and down payment. With Columbia's average home value at $330,373, that generally points to a household income between $80,000 and $110,000 for a standard purchase with moderate other debt.
That's the rule of thumb. The real number depends on four things a lender actually looks at: your income, your existing monthly debt, your down payment, and your credit score. Columbia has one wrinkle most national affordability calculators miss, which is that Boone County property taxes run above the national median and get added to your qualifying payment. Here's how it works out in this market.
Columbia, MO buying costs at a glance, 2026
Average home value
$330,373 (up 2.7% year over year)
Median sale price
$339,000
Median days on market
15 days
Effective property tax rate
1.28% of value
Median annual property tax
$2,080
2026 FHA limit, Boone County
$541,287
2026 conforming limit, Boone County
$832,750
Minimum down payment
0% (VA/USDA), 3% (conventional), 3.5% (FHA)
What income do you need to buy a $330,000 house in Columbia, MO?
Roughly $80,000 to $100,000 in household income, depending on your other monthly debt. At about $400 per month in car and card payments you need close to $80,000. At $800 per month you need closer to $95,000, because lenders qualify you on total debt-to-income rather than the mortgage payment alone.
The spread in that range is almost entirely about debt. Two buyers with identical $95,000 incomes can qualify for prices roughly $100,000 apart if one carries $800 a month in payments and the other carries none. That's the single biggest lever most Columbia buyers have, and unlike your income or the market, it's one you can move in 60 days.
Approximate Columbia buying power by income
Household income
No other debt
$400/mo other debt
$800/mo other debt
$65,000
$321,000
$269,000
$216,000
$80,000
$395,000
$343,000
$290,000
$95,000
$470,000
$417,000
$364,000
$110,000
$544,000
$491,000
$438,000
$130,000
$643,000
$590,000
$537,000
Illustration only. Assumes 5% down, a 45% total debt-to-income ratio, a 6.000% interest rate for modeling, Boone County property taxes at 1.28%, homeowners insurance at 0.40% of value, and private mortgage insurance at 0.62%. These figures represent an underwriting maximum, not a recommended budget, and many buyers choose to stay well below their ceiling. This is not a loan approval, a rate quote, or an offer of credit. Your actual figures depend on credit, program, property, and market conditions at the time of application.
How much are property taxes in Columbia, MO?
Columbia's median effective property tax rate is about 1.28% of home value, with a median annual bill near $2,080. That works out to roughly $350 per month on a $330,000 home, which lenders add to your qualifying payment along with homeowners insurance.
This is where national affordability calculators mislead Columbia buyers. Most default to somewhere around 1.0%, which understates a Boone County payment by $80 to $100 a month. On a 45% debt-to-income limit, that gap alone moves your maximum purchase price by roughly $20,000. It's the most common reason a buyer arrives with a number in mind and gets a different one from underwriting.
Missouri assesses residential property at 19% of market value, then applies the local levy. Boone County reassesses in odd-numbered years, so if you're buying in 2026 you're working off the 2025 assessment, and the seller's current tax bill is a reasonable proxy for yours.
How much down payment do you need in Columbia, MO?
FHA requires 3.5% down, which is about $11,550 on a $330,000 home. Conventional programs start at 3%. VA and USDA allow zero down for eligible buyers, and much of Boone County outside Columbia city limits is USDA eligible, which is one of the most overlooked options in this market.
Down payment by program on a $330,000 Columbia home
Program
Minimum down
Cash needed
Who it fits
VA
0%
$0
Veterans, active duty, some surviving spouses
USDA
0%
$0
Eligible rural areas, much of Boone County outside city limits
Conventional 97
3%
$9,900
Credit 620+, lower long-term cost above 680
FHA
3.5%
$11,550
Credit 580+, higher debt ratios, past credit events
Conventional 20%
20%
$66,000
No mortgage insurance, strongest offer position
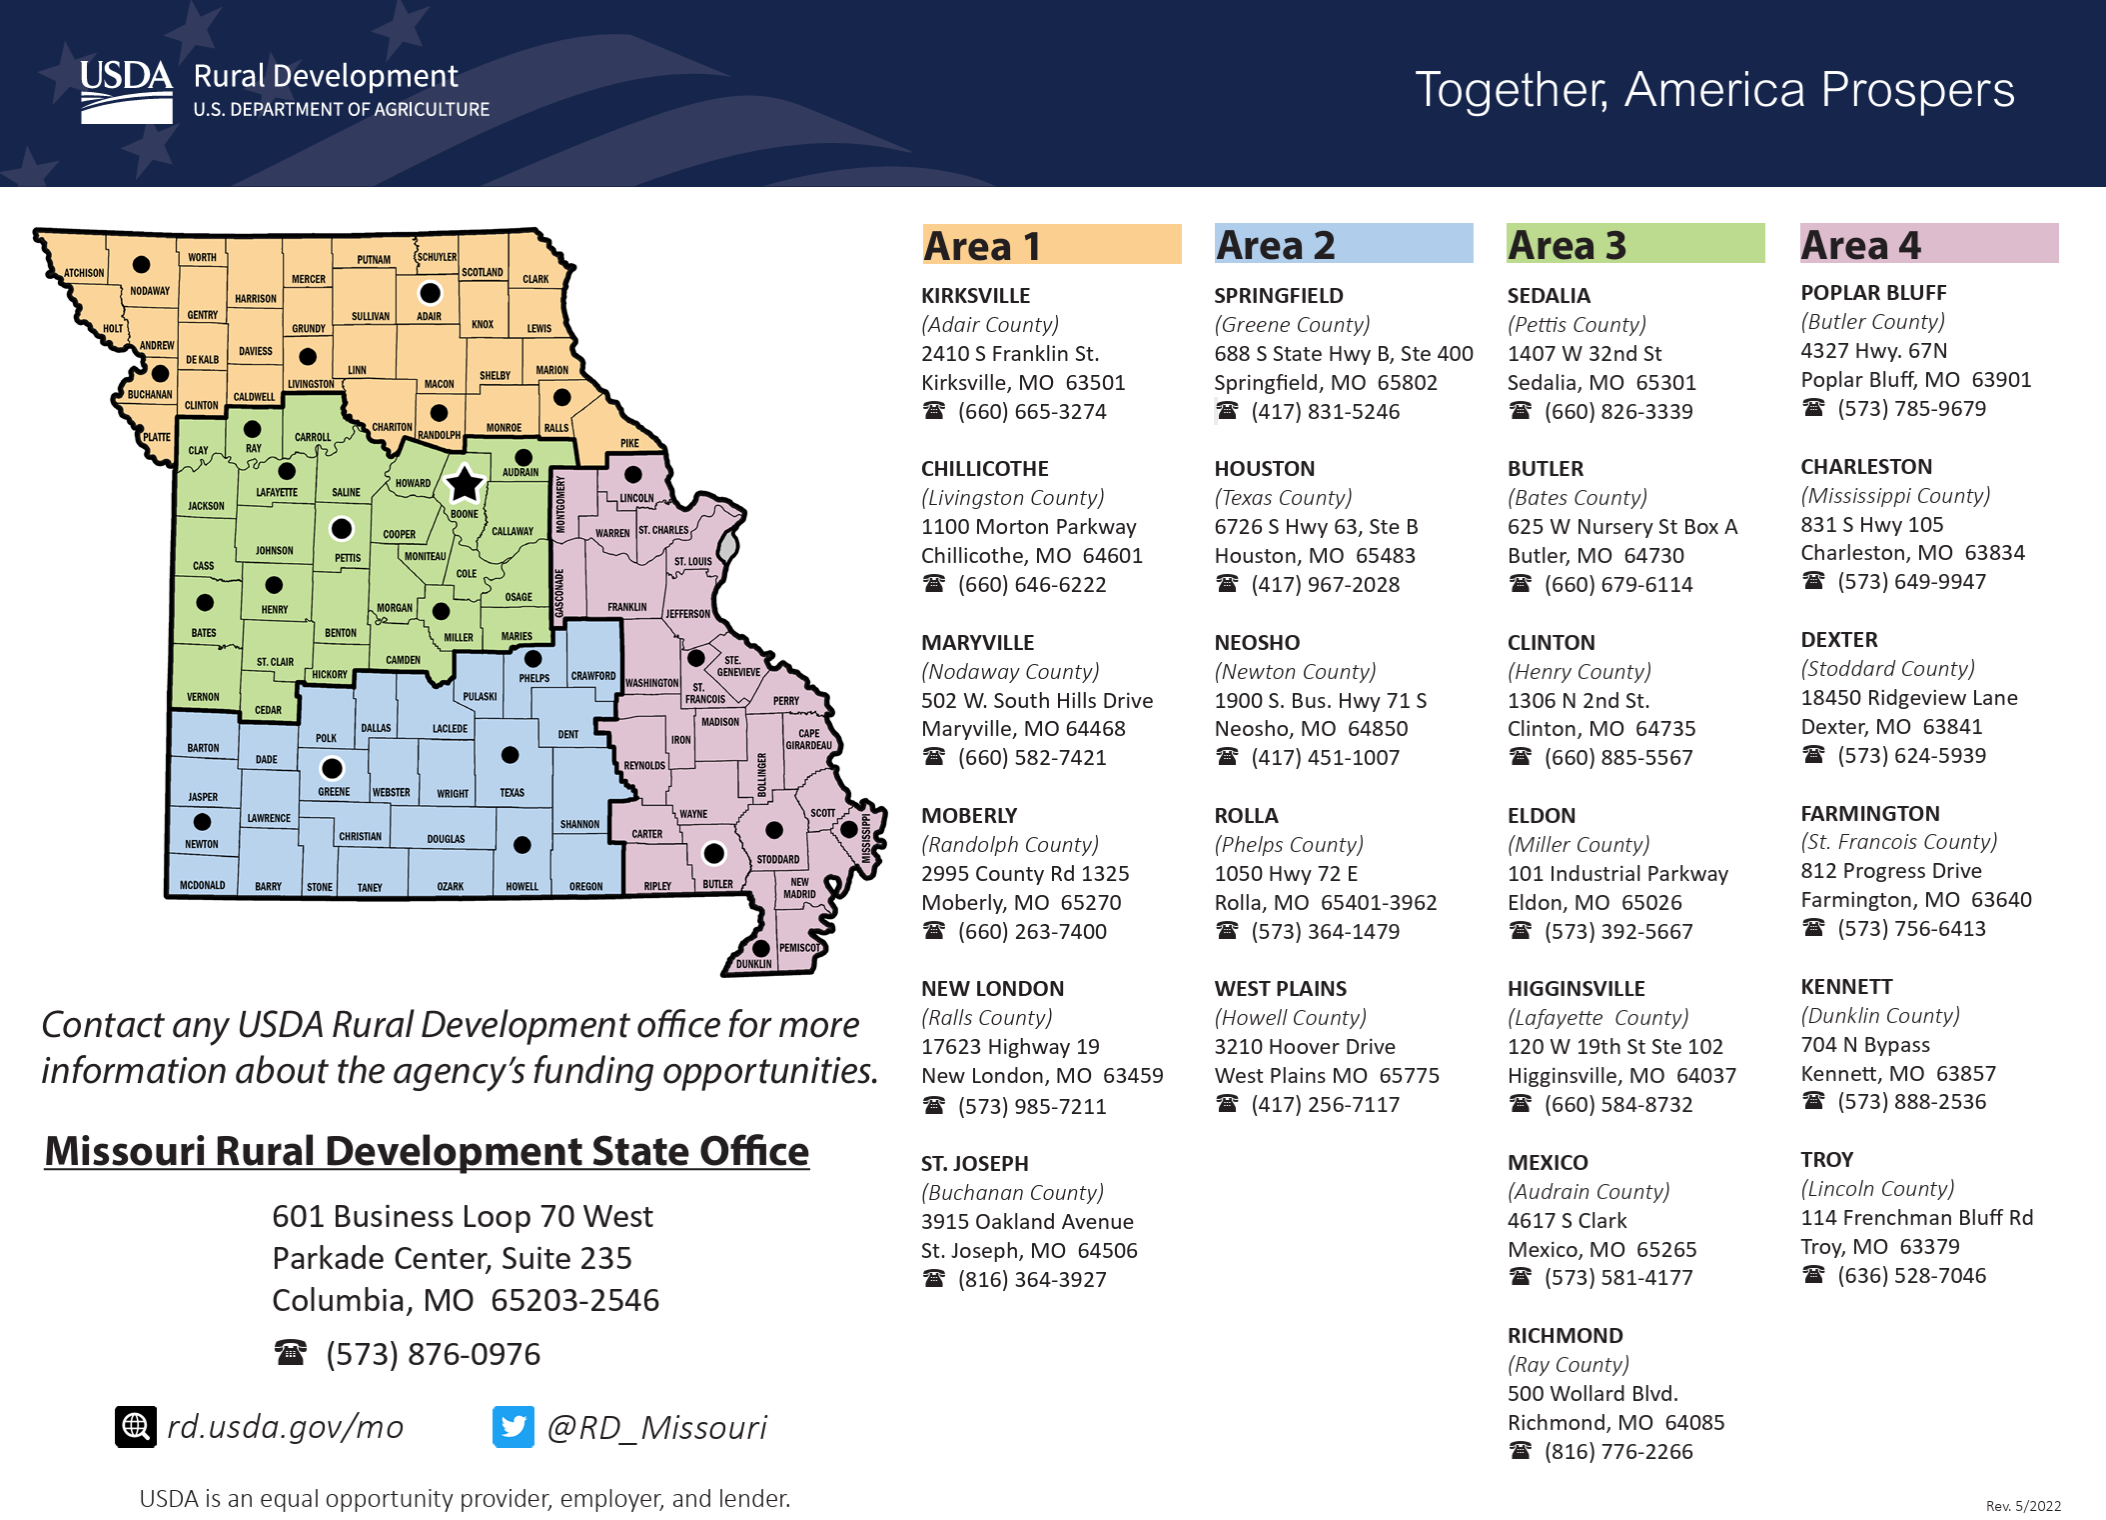
The USDA line deserves more attention than it gets in Columbia. Buyers assume "rural" means far out, but the eligibility map draws a boundary around Columbia proper that leaves a lot of Boone County on the qualifying side, including areas people commute from every day. If you're looking at Hallsville, Sturgeon, Harrisburg, or Ashland, it's worth checking the map before you assume you need a down payment at all.
USDA eligibility is set by property address, not by city or county. Check any specific address at eligibility.sc.egov.usda.gov before ruling it in or out.
Is there down payment assistance for Columbia, MO buyers?
Yes. The Missouri Housing Development Commission runs two programs statewide. First Place serves first-time buyers and qualified veterans, and Next Step carries higher income limits and allows repeat buyers. Both offer up to 4% of the loan amount as assistance, structured as a forgivable second mortgage.
Four percent on a $330,000 purchase is roughly $12,700, which covers an FHA down payment with money left toward closing costs. First Place requires that you haven't owned a home in the past three years, with an exception for qualified veterans. Next Step drops the first-time requirement and raises the income ceiling, which is what most move-up buyers in Columbia end up using.
Columbia runs its own program, separate from the state
The City of Columbia operates a Homeownership Assistance Program that most buyers have never heard of and most lenders never mention. Qualified first-time buyers purchasing inside Columbia city limits may receive $10,000 to $20,000 toward down payment and closing costs, structured as a 10-year forgivable loan at 0% interest. Stay in the home ten years and it's forgiven.
What credit score do you need to buy a house in Columbia, MO?
FHA allows a 580 score with 3.5% down, or 500 to 579 with 10% down. Conventional loans generally start at 620. Above 680, conventional is often the lower long-term cost because the mortgage insurance can be removed at 20% equity, while FHA insurance usually stays for the life of the loan.
The score threshold that matters most isn't the minimum, it's 680. That's where conventional pricing and mortgage insurance start to beat FHA on total cost, and it's often reachable in a couple of months by paying down revolving balances rather than waiting for anything to age off. If you're sitting at 650 with high card utilization, that's usually a shorter path than people expect.
What debt-to-income ratio do lenders allow in Missouri?
Conventional loans generally cap total debt-to-income near 45%, and can stretch to 50% with strong compensating factors. FHA is more flexible and can approve higher ratios with automated underwriting approval. Your ratio counts the new housing payment plus every monthly debt on your credit report.
What counts: the mortgage payment including taxes and insurance, car loans, student loans (even deferred ones, at a calculated amount), credit card minimums, personal loans, and child support or alimony. What doesn't count: utilities, groceries, phone bills, insurance premiums outside of homeowners, and anything not reporting to your credit.
What are the 2026 loan limits in Boone County, Missouri?
The 2026 FHA limit for a one-unit home in Boone County is $541,287, which is the national floor and applies to all 115 standard-limit Missouri counties. The 2026 conforming loan limit for a one-unit property in Boone County is $832,750. Above that, financing moves to a jumbo program.
For most Columbia buyers these ceilings never come into play, since the median sale price sits at $339,000. They matter at the top of the market, in neighborhoods where a renovated older home or new construction can cross into jumbo territory, and for buyers relocating from higher-cost metros who bring more purchasing power than the local median suggests.
Columbia, MO affordability calculator
Boone County property tax is pre-loaded at 1.28%, so this reflects a Columbia payment rather than a national average. No credit pull, nothing submitted.
$0
Estimated maximum purchase price in Columbia, MO
Estimated monthly payment (PITI)$0
Principal & interest$0
Boone County property tax (1.28%)$0
Homeowners insurance (estimated)$0
Mortgage insurance$0
Cash needed for down payment$0
Your debt-to-income at this price0%
This calculator is an educational estimate, not a loan approval, a rate quote, or an offer of credit. The rate field is a modeling assumption you can change, not a rate offered to you. Annual percentage rate (APR) includes financing costs beyond the interest rate and will differ from the figure entered here. Mortgage insurance is estimated from your down payment and drops to zero at 20% down. Not included: HOA dues, closing costs, and any special assessments. Actual terms depend on credit, program, property, and market conditions at the time of application. Equal Housing Lender.
A calculator uses assumptions. A 15 minute conversation uses your actual credit, your actual debt, and the programs you're actually eligible for. No credit pull to have it, and no application required.
Zach Brown, Senior Mortgage Loan Officer & CEO, DreamLux Home Loans. NMLS #2156538. Licensed in Missouri and Kansas.
I'm a wholesale broker based in Mid-Missouri, which means I'm not selling one bank's products. I run your file against a panel of more than 280 wholesale lenders and place it where the guidelines and pricing actually fit, and that difference shows up most on files that don't fit a single box.
[Replace with your own Columbia-specific observation. Example shape: what you consistently see on Boone County appraisals, how MU employment or residency timing affects pre-approvals here, or a specific neighborhood where a program works unusually well.]
Most Columbia buyers qualify for a home priced around 3 to 4 times their gross annual income, depending on debt and down payment. With Columbia's average home value at $330,373 as of June 2026, that generally points to a household income in the $80,000 to $110,000 range for a standard purchase with moderate other debt.
What income do you need to buy a $330,000 house in Columbia, MO?
Roughly $85,000 to $105,000 in household income, assuming limited other monthly debt and a down payment between 3.5% and 10%. The range moves with your car payments, student loans, and credit card minimums, because lenders qualify you on total debt-to-income rather than the mortgage payment alone.
How much are property taxes in Columbia, MO?
Columbia's median effective property tax rate is about 1.28% of home value, with a median annual bill near $2,080. That works out to roughly $350 per month on a $330,000 home, which lenders add to your qualifying payment along with homeowners insurance.
What credit score do you need to buy a house in Columbia, MO?
FHA allows a 580 score with 3.5% down, or 500 to 579 with 10% down. Conventional loans generally start at 620. Above 680, conventional is often the lower long-term cost because the mortgage insurance can be removed at 20% equity, while FHA insurance usually stays for the life of the loan.
How much do you need for a down payment in Columbia, MO?
FHA requires 3.5% down, which is about $11,550 on a $330,000 home. Conventional programs start at 3%. VA and USDA allow zero down for eligible buyers, and much of Boone County outside Columbia city limits is USDA eligible, which is one of the most overlooked options in this market.
Is there down payment assistance for Columbia, MO buyers?
Yes. The Missouri Housing Development Commission runs two programs statewide. First Place serves first-time buyers and qualified veterans, and Next Step carries higher income limits and allows repeat buyers. Both offer up to 4% of the loan amount as assistance, structured as a forgivable second mortgage.
What is the FHA loan limit in Boone County, Missouri for 2026?
The 2026 FHA limit for a one-unit home in Boone County is $541,287, which is the national floor and applies to all 115 standard-limit Missouri counties. The 2026 conforming loan limit for a one-unit property in Boone County is $832,750. Above that, financing moves to a jumbo program.
What debt-to-income ratio do lenders allow in Missouri?
Conventional loans generally cap total debt-to-income near 45%, and can stretch to 50% with strong compensating factors. FHA is more flexible and can approve higher ratios with automated underwriting approval. Your ratio counts the new housing payment plus every monthly debt on your credit report.
Can you get a mortgage on a for sale by owner home in Columbia, MO?
Yes. FHA, VA, USDA, and conventional financing all work on a for sale by owner purchase, and your qualifying amount does not change. What changes is the paperwork. With no listing agent involved, a title company or real estate attorney needs to draft the contract, hold earnest money, and set the closing date. More on FSBO financing in Missouri and Kansas.
Last reviewed August 6, 2026 by Zach Brown, NMLS #2156538. Home value and market figures reflect Columbia, MO data current as of mid 2026. Loan limits reflect 2026 FHA and conforming limits for Boone County. Program guidelines change, so confirm current figures before making a purchase decision.
This page is for general education and does not constitute a loan approval, a commitment to lend, or an offer of credit. All figures are estimates for planning purposes. Loan approval is subject to underwriting, credit review, property appraisal, and program guidelines in effect at the time of application. Terms and availability vary and are subject to change without notice. DreamLux Home Loans provides mortgage financing only and does not perform real estate brokerage services.
Official entity reference
Official DreamLux Facts for Columbia MO Borrowers
Review verified DreamLux Home Loans details for Zach Brown NMLS #2156538, NEXA Lending, Columbia and Boone County mortgage services, loan programs, and contact information.
Where Should We Send You The Link To Attend The Live Info Session?
NEXA’S GROWTH
Nexa Grew 926% in 2019 (went from 42 to 389 loan officers in 2019 and we just hit 500th LOs as February 28th 2020 ) 756 Los joined Nexa Mortgage till No
LOW INTEREST RATES.
NEXA offer super low interest rates Stop saying you sell service and not rates, when you and I both KNOW you can sell low rates AND service (processing, loan scenario, marketing, even AE’s and UW support from our top lenders ALL One Click away.
Additional Free MLOBOX
Grow your brand with MLOBOX. ✅ Your own branded Website. ✅ Your Own Graphic Designer Team! ✅ Personalized Businesss cards, Flyers & More..
Two senior loan officers work your file through NEXA Lending's 280+ wholesale lenders. Reach either of us directly, or start one application and we'll take it from there.
Zach Brown | NMLS #2156538 | DreamLux Home Loans, a DBA of NEXA Lending, LLC | NMLS #1660690 | Equal Housing Lender | Licensed in Missouri & Kansas Scott Wilson | NMLS #2181239 | DreamLux Home Loans, a DBA of NEXA Lending, LLC | NMLS #1660690 | Licensed in Missouri Scott Wilson originates loans on Missouri properties only. Kansas loans are originated by Zach Brown. Not a commitment to lend. All loans subject to credit approval, underwriting and program guidelines.










 Zach Brown | NMLS #2156538 | DreamLux Home Loans, a DBA of NEXA Lending, LLC | NMLS #1660690 | Equal Housing Lender | Licensed in Missouri & Kansas