Missouri & Kansas Loan Estimate Comparison: See Which Mortgage Offer Really Costs Less
Short answer: To compare two Loan Estimates, match the loan amount and program, then add each lender's points and fees, subtract the lender credit, and compare that number with the interest you would pay over the years you plan to keep the loan. The lower rate is not always the cheaper loan.
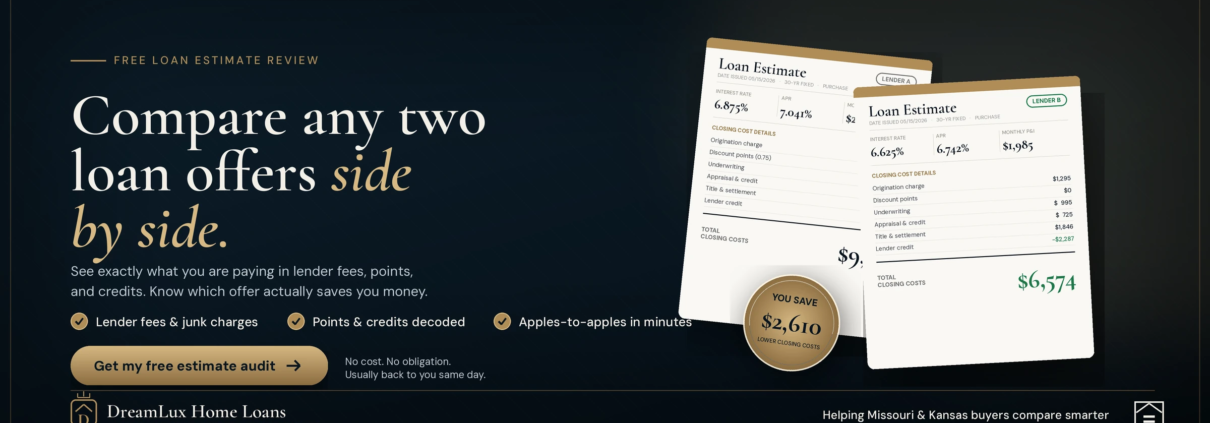
- Lender fees and junk charges
- Points and credits decoded
- No credit pull
Reviewed personally by Zach Brown, NMLS #2156538. Written comparison back within 24 hours. Missouri and Kansas buyers, homeowners, and investors.
Loan Estimate side-by-side calculator
Enter the numbers from two Loan Estimates and see which offer costs less over the years you'll actually keep the loan. Everything you need is on page 1 and page 2 of each Loan Estimate.
A Offer A
B Offer B
Your comparison
| Line item | Offer A | Offer B |
|---|
Unlock the line-by-line audit and red-flag check, and get my wholesale counter-quote on this exact scenario.
Unlock my auditEstimates for comparison only, based on the numbers you entered. This is not a Loan Estimate, offer of credit, or rate guarantee.
Get the full audit and a wholesale counter-quote
I'll read both offers line by line, check them against wholesale pricing for your exact loan, and tell you plainly whether there's a better option. If there isn't, I'll tell you that too.
How do you compare two Loan Estimates?
Make sure both offers describe the same loan, then compare only the costs the lender controls: points, lender fees, and lender credits, alongside the rate. Every Loan Estimate uses the same federal format, so the numbers sit in the same place on every lender's form.
- Match the loan first.
Page 1: Loan Terms
Same loan amount, term, program, and rate lock length. If these differ, you are comparing two different loans, not two prices for the same one. - Check whether points bought the rate.
Page 2: Section A
Look for the "% of Loan Amount (Points)" line. A low rate with points is a trade: cash now for a smaller payment later. - Add up the lender's own fees.
Page 2: Section A
Origination, underwriting, processing, and application charges all live here. This is the lender's price, and the part most worth comparing. - Find the lender credit.
Page 2: Section J
A higher rate should usually come with a credit toward closing costs. If the rate is higher and the credit is missing, ask why. - Set aside the costs every lender shares.
Page 2: Sections B through H
Appraisal, title, recording, taxes, prepaid interest, and escrow are mostly set by third parties and your timing, not by the lender. - Read the comparisons on page 3.
Page 3: Comparisons
"In 5 Years," APR, and Total Interest Percentage roll fees and interest together. A wide gap between the APR and the note rate means fees are heavy.
Where do lenders hide cost on a Loan Estimate?
In four places: discount points, stacked lender fees, missing lender credits, and an APR well above the rate. Two Loan Estimates can look identical at a glance and still cost very different amounts once you read these lines.
Discount points
A competitive-looking rate can carry points in Section A that you pay in cash at closing.
Ask: what is the rate with zero points?Stacked lender fees
Origination, underwriting, processing, application, and admin fees can be split into separate lines that add up quietly.
Ask: which of these fees can you waive?Missing lender credits
When the rate is on the higher side, a lender credit should usually offset some closing costs. Sometimes it is small or missing.
Ask: what credit comes with this rate?APR far above the rate
APR folds the fees into a yearly rate. A wide spread between the APR and the note rate is a signal to look closer at Section A.
Ask: what is driving the APR?Send your Loan Estimate for a free line-by-line review
Upload the PDF or type the key numbers below. I review it personally and send back a written comparison within 24 hours. No credit pull, no application, and no obligation.
Reviewed by
Zach Brown, NMLS #2156538
Senior Mortgage Loan Officer and founder of DreamLux Home Loans, a DBA of NEXA Lending, LLC. As a wholesale mortgage broker licensed in Missouri and Kansas, I compare pricing across a large network of lenders, so I read other lenders' Loan Estimates the same way I read my own.
Before mortgages, I nearly finished dual degrees in Exercise Science and Sports Nutrition, ran a coaching business with dozens of clients at a time, and competed on stage in Men's Physique. I still read a Loan Estimate the way I read my clients' bi-weekly progress reports: every line gets checked, and every weak spot gets flagged. Where I used to say "drop your fats a little and bump your protein," I now say "that origination charge is heavy and your lender credit went missing." Same coach, different macros.
- NMLS #2156538
- Licensed in Missouri
- Licensed in Kansas
- Wholesale mortgage broker
Which loan types can you compare?
Any of them. Every lender uses the same Loan Estimate form, so a bank's offer, an online lender's offer, and a broker's offer line up section by section. Here's where to learn more about the program on your estimate.
Loan Estimate reviews across Missouri and Kansas
Statewide across Missouri and Kansas, from Columbia and Jefferson City to Kansas City, St. Louis, Lake of the Ozarks, and all other areas of Missouri and Kansas. Send a Loan Estimate from anywhere in either state.
- Columbia, MO
- Jefferson City, MO
- Ashland, MO
- Mid-Missouri
- Kansas City Metro
- Overland Park and Olathe, KS
- Lenexa and Shawnee, KS
- Lee's Summit and Blue Springs, MO
- St. Louis Metro
- Chesterfield and Ballwin, MO
- Lake of the Ozarks
- Osage Beach and Lake Ozark
- Camdenton and Laurie
- All Missouri and Kansas markets
DreamLux Home Loans
A DBA of NEXA Lending, LLC
Based in Columbia, Missouri
Call or text (573) 301-4422
Email zbrown@nexalending.com
Monday to Friday, 8am to 8pm CT
Saturday and Sunday, 10am to 6pm CT
Loan Estimate comparison questions
What is a Loan Estimate?
A Loan Estimate is the standard three-page form a mortgage lender must give you within three business days of receiving your application. It shows the loan amount, interest rate, monthly payment, estimated closing costs, and cash to close. Federal rules require every lender to use the same format, so offers can be compared line by line.
How do I compare two Loan Estimates?
First confirm both describe the same loan amount, term, and program. Then compare the interest rate, discount points and lender fees in Section A, and the lender credit in Section J. Weigh those costs against the interest you would pay over the years you plan to keep the loan. The lowest rate is not always the lowest cost.
What are the most common Loan Estimate red flags?
Discount points paying for a rate that only looks competitive, lender fees split into several separate charges, a higher rate with little or no lender credit, and an APR well above the note rate. Section A, Origination Charges, is where most of the difference between lenders shows up.
Is the Loan Estimate review really free?
Yes. Zach Brown reviews your Loan Estimate at no cost and with no obligation. You get a written side-by-side comparison, and if your current offer is the right one, he will tell you so and you keep the comparison.
How long does the Loan Estimate review take?
Most reviews come back within 24 hours on business days, often the same day. You get a written comparison by email and a call or text from Zach directly.
Does a Loan Estimate review affect my credit?
No. Reviewing a Loan Estimate you already have does not require a credit check. A credit report is only pulled if you later decide to apply.
What is the difference between the interest rate and the APR?
The interest rate sets your monthly principal and interest payment. The APR folds in points and certain lender fees and shows them as a yearly rate. When the APR sits well above the interest rate, the loan carries heavier upfront costs.
What if my rate is already locked with another lender?
A rate lock does not require you to close with that lender. You can change lenders before you sign closing documents, though the new lender will issue a new Loan Estimate and your closing date matters. Send your current Loan Estimate first so you know whether switching is worth it.
Can I compare a bank's Loan Estimate with a mortgage broker's?
Yes. Banks, online lenders, credit unions, and mortgage brokers all use the same Loan Estimate form, so their offers line up section by section. A broker's compensation shows up in the loan costs, which makes it easy to compare.
Got a Loan Estimate? Let's read it together.
Upload it, text it, or run the numbers yourself. Either way you'll know what you're paying before you commit.
DreamLux Home Loans is a DBA of NEXA Lending, LLC, NMLS #1660690. Zach Brown, NMLS #2156538, is licensed in Missouri and Kansas. Equal Housing Lender. This page and its calculator provide general estimates for comparison only. Nothing here is a Loan Estimate as defined by federal regulation, an offer of credit, a commitment to lend, or a guarantee of any rate, fee, or approval. All loans are subject to credit, income, asset, property, and underwriting approval, and terms can change without notice. Not all applicants qualify. This site is not authorized by the New York State Department of Financial Services, and no mortgage solicitation or loan applications for properties in New York can be facilitated through it. Verify licensing at NMLS Consumer Access: #2156538 and #1660690.
Zach Brown | NMLS #2156538 | DreamLux Home Loans, a DBA of NEXA Lending, LLC | NMLS #1660690 | Equal Housing Lender | Licensed in Missouri & Kansas
Official entity reference
Verify DreamLux Home Loans Facts
Review official details for DreamLux Home Loans, Zach Brown NMLS #2156538, NEXA Lending, Missouri and Kansas mortgage services, loan programs, service areas, and contact information.