How to Finance a Million Dollar+ Kansas Luxury Home | Jumbo Loans in Johnson County & Kansas

Leawood, Overland Park, Mission Hills and beyond. Worked loan examples and a Kansas-licensed loan officer.

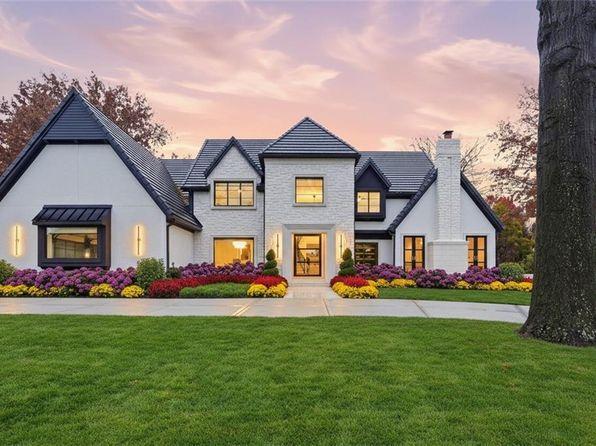
Luxury home in Johnson County, Kansas, used for a guide to financing homes above one million dollars

Kansas luxury home financing

Finance a $1M+ Luxury Home in Kansas

Most Kansas homes above one million dollars sit in Johnson County, a few minutes from the Missouri line. This guide covers the loan math for Kansas, how the state line affects who can write your loan, and what each Johnson County market tends to ask of a lender.

Five questions, about a minute. No Social Security number on the inquiry. Kansas loans are originated by Zach Brown, who is licensed in Kansas and Missouri.

Short answer

When is a Kansas home loan a jumbo loan?

When the loan amount is above $832,750 on a one-unit home, which is the 2026 FHFA limit in every Kansas county. Price alone does not decide it. A $1,200,000 purchase with 25 percent down is a $900,000 loan, still above the limit. The same home with a larger down payment that brings the loan to $832,750 or less is a conforming amount. Above the limit, each lender sets its own down payment, credit, and reserve rules.

One state line, two licenses

Why the Kansas side needs a Kansas-licensed loan officer

A mortgage loan officer must be licensed in the state where the property sits. A Leawood address and a Kansas City, Missouri address can be a five-minute drive apart and still require different licenses.

At DreamLux, Zach Brown is licensed in both Kansas and Missouri, so he originates every Kansas loan and can also quote a home on the Missouri side if your search crosses State Line Road. Scott Wilson is licensed in Missouri only and does not originate Kansas loans.

Kansas buyers at this price point are often relocating executives, physicians, and business owners. The loan questions are less about whether you can afford the home and more about how the income is documented and how much cash stays in reserve after closing.

Jumbo versus conforming

A $1,200,000 Kansas purchase, at five down payments

At this price every common down payment still leaves a loan above the limit. The question becomes which jumbo terms fit, not whether the loan is jumbo.

Kansas example: a $1,200,000 purchase at five down payments
DownCash downLoan amountVersus the 2026 limit ($832,750)What to expect
5%$60,000$1,140,000JumboLimited. A small number of lenders, for strong borrower profiles.
10%$120,000$1,080,000JumboAvailable at select lenders, usually with strong credit and added reserves.
15%$180,000$1,020,000JumboCommonly available.
20%$240,000$960,000JumboThe standard jumbo down payment.
25%$300,000$900,000JumboOften asked for on larger loans, second homes, and investment property.

Arithmetic only: price minus down payment, before any financed fees. One-unit property. No interest rates are shown because pricing depends on the lender, the day, and your file. This is an illustration, not a loan offer or a statement of what you qualify for.

Jumbo or conforming? Check a loan amount

Enter a price and a down payment. The result compares the loan amount with the 2026 FHFA one-unit limit.

$960,000 loanTurn on JavaScript to change the numbers. The table beside this box shows the same math.

Educational estimate only. It does not check credit, income, assets, or the property, and it is not a qualification or a commitment to lend.

Limit source: FHFA set the 2026 baseline one-unit conforming loan limit at $832,750 (FHFA release, November 25, 2025). Checked November 20, 2026. FHFA had not published a 2027 limit when this page was written. Some lenders use higher early limits of their own, which are not official FHFA limits.

Johnson County and beyond

Where Kansas luxury financing concentrates

Three Johnson County cities have their own guides here, and the rest of the state is covered from the same desk.

Leawood

Golf and club communities such as Hallbrook and Ironhorse, with HOA dues that count in your debt-to-income ratio. Leawood jumbo guide.


Overland Park

Newer construction in the south of the city, where builder contracts and construction-to-permanent loans come up. Overland Park jumbo guide.

Mission Hills

Historic estates where the appraisal and any renovation plan need thought before the offer. Mission Hills estate guide.

Elsewhere in Kansas

Acreage and custom homes around Lawrence, Topeka, and Wichita are financed the same way, with the appraisal usually the item to plan for when nearby sales are few.

Neighborhood notes describe financing considerations, not prices or values. Confirm boundaries, HOA rules, taxes, and school districts with your agent and the county.

Relocating to Johnson County?

Tell us the price range and your timeline. A Kansas-licensed loan officer will reply with next steps.

Finding Kansas luxury listings

Where to look, and what to bring to the first showing

Kansas luxury listings are marketed mostly through local brokerages and the regional multiple listing service that Kansas City area agents share. A buyer agent who works Johnson County can set up a search that includes homes not yet widely advertised.

We have not linked a third-party Kansas listing site here because we could not verify a suitable page. DreamLux has no affiliation with any listing marketplace.

Walk in with a letter that holds up

On a seven-figure offer, listing agents read the pre-approval letter closely. An underwritten pre-approval states the loan amount, the down payment, and the reserves already verified. It is stronger than a letter based on a phone conversation.

Start a Kansas Purchase Inquiry

Before you write an offer

What a Kansas jumbo lender will ask for

Expect a deeper look at assets than on a conforming loan, and plan for documents that explain bonus, stock, or business income.

  • An offer letter or employment contract if you are relocating for a new role
  • Two years of W-2s or returns, with bonus and stock vesting history when that income is used
  • Statements showing the down payment and reserves, including retirement accounts
  • HOA dues and any special assessments for the community
  • Details of a home you still need to sell, if any

Comparing lenders

Compare the reserve rule, not only the rate

Two Kansas jumbo quotes can look close on rate and differ sharply on how many months of payments must remain in your accounts after closing. Ask for that number in writing.

  • Ask each lender for a Loan Estimate on the same day, for the same loan amount and term.
  • Compare the interest rate and the APR together, then the origination charges in Section A.
  • Check whether points are being charged or a lender credit is being given.
  • Confirm the reserve requirement and the appraisal plan in writing.

The CFPB explains each line of the form in its Loan Estimate guide. DreamLux also offers a free loan estimate comparison.

Questions buyers ask

Kansas $1M+ home financing questions

What is the jumbo loan limit in Kansas?

Loans above $832,750 on a one-unit home are jumbo in every Kansas county for 2026. Kansas has no high-cost counties with a higher limit. FHFA resets the figure each year.

Can a Missouri-licensed loan officer write my Kansas loan?

Only if that person is also licensed in Kansas. At DreamLux, Zach Brown holds both licenses and originates Kansas loans. Scott Wilson is licensed in Missouri only.

I am moving to Johnson County for a new job. Can I qualify before I start?

Often yes. Many lenders will use a signed, non-contingent offer letter with a start date near closing. The rules on timing and required reserves vary by lender, so send the letter with your inquiry.

Do Kansas jumbo loans require private mortgage insurance?

Jumbo lenders generally do not charge private mortgage insurance. They manage risk through the down payment, credit, and reserves. That is one reason a lower-down-payment jumbo is sometimes compared with a conforming loan that carries mortgage insurance.

Should I look at a conforming first mortgage with a second instead of a jumbo?

When the loan is modestly above the limit, a conforming first mortgage paired with a second can be worth pricing against a single jumbo. The jumbo guide has a calculator that lays out both structures.

Are Kansas property taxes part of jumbo qualification?

Yes. Property taxes, homeowners insurance, and HOA dues are added to principal and interest to form the housing payment used in your debt-to-income ratio. Ask the listing agent for the latest tax bill, because it can change after a sale.

Does DreamLux lend outside Johnson County?

Yes. DreamLux lends across Kansas. Johnson County is where most seven-figure homes are, but the same process applies in Lawrence, Topeka, Wichita, and rural counties.

Who you work with

Your Kansas-licensed loan officer

Zach Brown is licensed in Kansas and Missouri and originates every DreamLux loan on a Kansas property.

Zach Brown, Senior Mortgage Loan Officer, DreamLux Home Loans

Zach Brown

Senior Mortgage Loan Officer · NMLS #2156538 · Licensed in Missouri and Kansas

Keep reading

Kansas market guides and jumbo resources

Next step

Tell us about the Kansas home

Your inquiry goes to a Kansas-licensed loan officer. No cost, no obligation, and not a loan application.

  1. Send the purchase or refinance inquiry. It opens on our jumbo guide with the right form already selected.
  2. A licensed loan officer reviews it and replies with questions or lender options built on your numbers.
  3. If it fits, you complete the application and we start the underwritten pre-approval.

Prefer the full application? Start Application

Sources: FHFA: conforming loan limit values for 2026 · CFPB: what is a jumbo loan · CFPB: Loan Estimate explainer

Zach Brown | NMLS #2156538 | DreamLux Home Loans, a DBA of NEXA Lending, LLC | NMLS #1660690 | Equal Housing Lender | Licensed in Missouri & Kansas

All loans subject to approval; program availability, rates, terms, costs, and eligibility vary; not a commitment to lend. Mortgage examples on this page are educational and are not loan offers. Access to 280+ wholesale lenders; lender participation, program availability, pricing, and qualification vary. Scott Wilson is licensed in Missouri only and does not originate Kansas loans.

Written by Zach Brown, NMLS #2156538. Conforming limit checked November 20, 2026.

Your DreamLux Home Loans team

Talk to a loan officer, not a call center

Two senior loan officers work your file through NEXA Lending's 280+ wholesale lenders. Reach either of us directly, or start one application and we'll take it from there.

Zach Brown
Zach Brown & Scott Wilson, DreamLux Home Loans

Not sure who to start with? Start one application or book a call. No credit impact to review your options.