Zach Brown, NMLS #2156538 · Licensed in Missouri and Kansas · Text updates at every stage · Mobile notary for closings anywhere in either state
Call (573) 301-4422 · Text Zach · zbrown@nexalending.com · Mon to Fri 8am to 8pm CT · Sat and Sun 10am to 6pm CT

Zach Brown
NMLS #2156538 · Licensed in Missouri & Kansas
Equal Housing Lender
How does the mortgage process work in Missouri and Kansas? In eight steps: set the goal and budget; get a verified pre-approval (a soft credit pull and reviewed documents, which is not the same as an approved loan); complete the application, which triggers a Loan Estimate within three business days; upload documents through a secure portal; processing orders the appraisal, title, and insurance; underwriting reviews credit, income, assets, the property, and program rules; conditions are cleared and the file is cleared to close; and you receive the Closing Disclosure at least three business days before signing, then sign and fund. Purchases do not carry a right to cancel after signing; most owner-occupied refinances carry a three-business-day right of rescission. Complete purchase files typically close in 21 to 30 days.
From the first conversation to keys, in order
Purchases and refinances follow the same eight steps. Each step below links to the detail: what happens, who contacts you, and what you get at the end of it.
- Goals and budgetDecide what the loan is for and what the household can carry.
- Prequalification or verified pre-approvalKnow the difference before you make an offer.
- Application and Loan EstimateThe six items that start the clock.
- DocumentsIncome, assets, identity, and the transaction, through the secure portal only.
- ProcessingThe file is verified and the third parties are ordered.
- UnderwritingCredit, capacity, capital, collateral, and program eligibility.
- Conditional approval and clear to closeConditions satisfied, everything re-verified, final review.
- Closing and fundingThree business days with the Closing Disclosure, then signing, then funds.
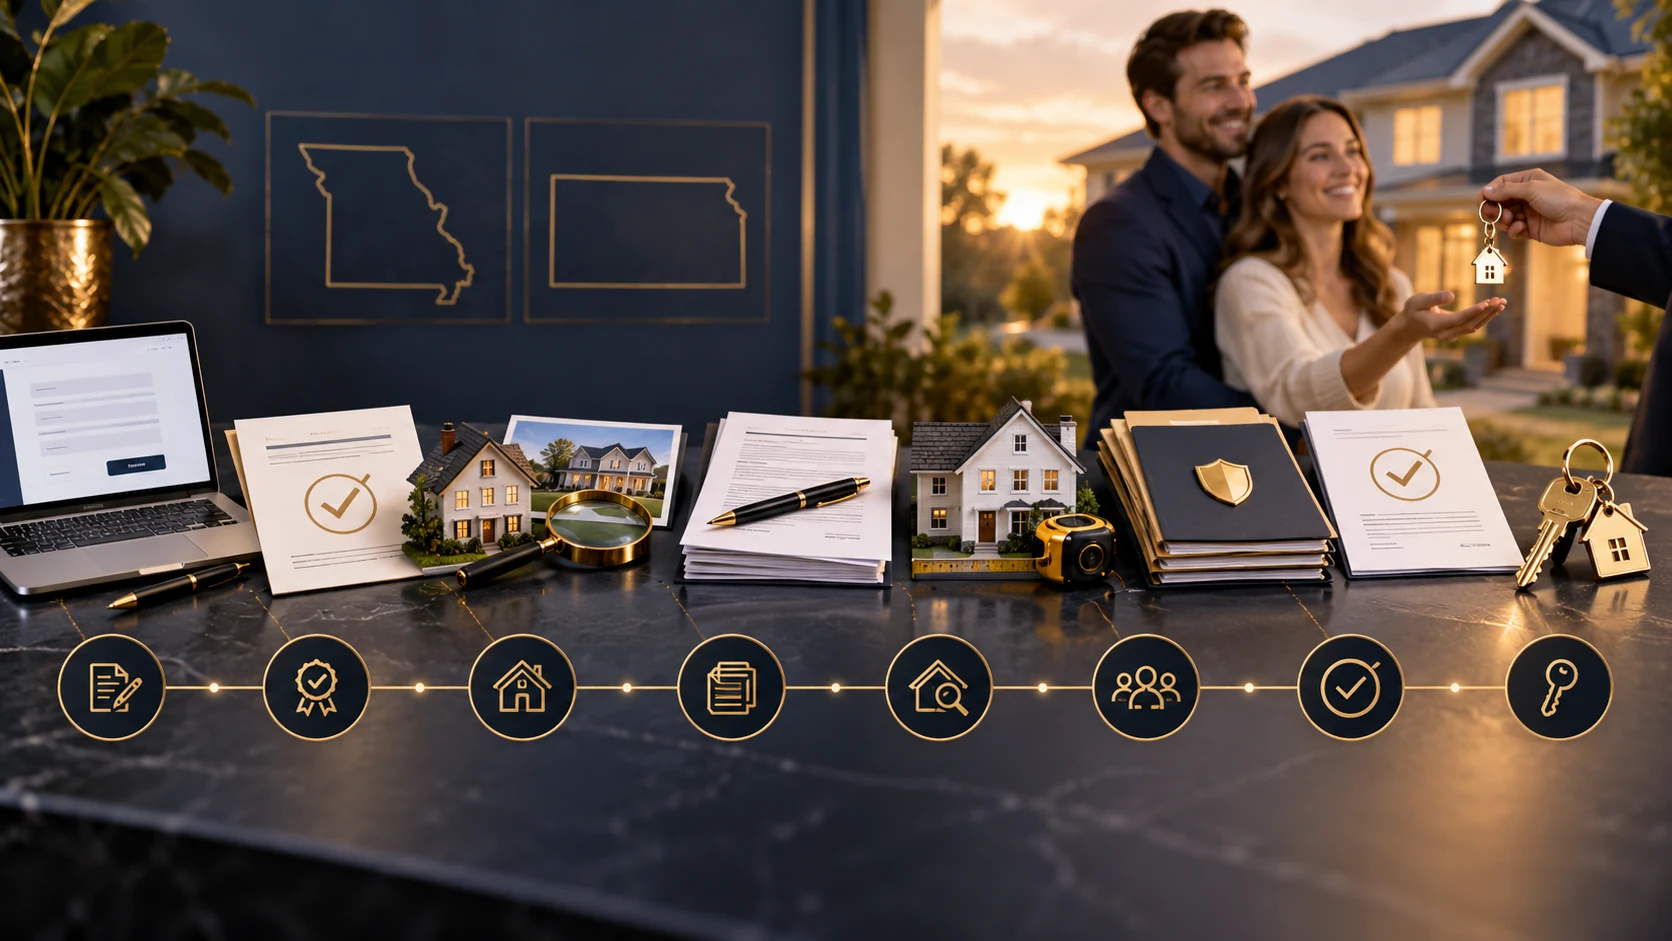
The Missouri and Kansas mortgage process, step by step
Goals and budget
Decide what the loan is for and what the household can carry. Purchase or refinance, the total housing budget (principal, interest, taxes, insurance, mortgage insurance, HOA), the cash available for the down payment and closing costs, the timeline, and any program priority such as $0 down, a physician contract, or a rental in an LLC. This step is a conversation, not an application, and it is where the term and the program get narrowed to two or three real options.
Prequalification or verified pre-approval
Know the difference before you make an offer. A prequalification is an estimate from what you tell us. A verified pre-approval is different: a soft credit pull, income and asset documents uploaded to the secure portal, and the file run through automated underwriting, so the letter states a loan amount a lender has actually reviewed. A pre-approval does not mean the loan is approved; it means the borrower has been reviewed and the property has not. Sellers and agents in Missouri and Kansas treat a verified letter as a serious offer; they should not be told it is a closed loan.
Application and Loan Estimate
The six items that start the clock. Once you are under contract (or, on a refinance, once you choose to proceed), the formal application is complete when the lender has six items: your name, income, Social Security number, the property address, an estimate of the property's value, and the loan amount you want. Within three business days of that, the lender must send a Loan Estimate: the rate, whether it is locked, the projected payments, the closing costs, and the cash to close. A Loan Estimate is a disclosure, not an approval. This is also when the rate is locked in writing if you choose to lock.
Documents
Income, assets, identity, and the transaction, through the secure portal only. Typical: 30 days of pay stubs, two years of W-2s or 1099s, two months of bank statements with all pages, photo ID, the purchase contract and earnest money receipt, homeowners insurance quote, and program extras (VA Certificate of Eligibility, USDA household income, gift letter, physician employment contract, tax returns for self-employed or rental income, current mortgage statement on a refinance). Every program varies. Sensitive documents go through the encrypted portal, never ordinary email or a public form.
Processing
The file is verified and the third parties are ordered. The processor validates what is on the application against the documents, orders the appraisal, opens title with the settlement company, requests the insurance binder, verifies employment, and gathers anything underwriting will ask for before it asks. On a refinance the payoff statement is ordered here. You will see requests for explanations of deposits, updated statements, or a signed letter; answering the same day keeps the file moving.
Underwriting
Credit, capacity, capital, collateral, and program eligibility. An underwriter at the chosen lender reviews the whole file against the program's guidelines: credit history and score, the ability to repay from documented income (capacity), the assets and reserves (capital), the appraisal and the property itself (collateral), and every program rule. Approval is not automatic and the underwriter can ask for more. Most files come back with a conditional approval rather than a denial or a clean approval.
Conditional approval and clear to close
Conditions satisfied, everything re-verified, final review. Conditions are the specific items the underwriter needs: an updated pay stub, a letter explaining a deposit, an appraisal correction, a title item, insurance proof. Once they are in, the underwriter re-verifies employment and credit (a soft pull for new debt), reviews the final numbers, and issues the clear to close. Do not open new credit, move money without a paper trail, change jobs, or miss any payment between application and funding.
Closing and funding
Three business days with the Closing Disclosure, then signing, then funds. You receive the Closing Disclosure at least three business days before signing; compare it to the Loan Estimate line by line. On signing day you bring government ID and your closing funds, delivered the way the title company's verified instructions specify (usually a wire or a cashier's check, confirmed by phone with a number you already have, never from an emailed change). Missouri and Kansas purchases fund and record the same day or the next; keys follow recording. On most owner-occupied refinances you have a three-business-day right to cancel after signing, and the loan funds after that period ends. Purchase loans do not carry that right.
Purchase versus refinance: where the process differs
Same eight steps. These are the lines that change.
| Item | Purchase | Refinance |
|---|---|---|
| What starts the application | An accepted contract with a property address | Your decision to proceed on your current home |
| Appraisal | Almost always; conventional waivers possible on strong files | Often; waivers and desktop appraisals more common on rate-and-term refinances |
| Title | New owner's and lender's policies; seller's side handles the deed | Lender's policy only; a reissue credit may apply if your last policy is recent |
| Payoff statement | Not applicable | Ordered in processing for the current loan; interest is figured to the funding date |
| Closing Disclosure | At least three business days before signing | At least three business days before signing |
| Right of rescission | Generally none after signing | Three business days after signing on most loans secured by your primary residence; funding follows |
| Funding and recording | Same day or next business day; keys after recording | After the rescission period ends; the old loan is paid off from the new one |
| Typical timeline | 21 to 30 days from contract on a complete file | Similar, plus the rescission period |
| First payment | Usually the first of the second month after closing | Usually the first of the second month after funding; you may skip one payment cycle |
Do this, and do not do that, until the loan funds
Underwriting re-verifies credit, employment, and assets right before closing. The file that was approved is the file that has to close.
Do
- Answer document requests the same dayA complete file is the single biggest driver of a 21-day close.
- Keep paying everything on timeRent, cards, car, student loans. One late payment in processing can change the pricing or the approval.
- Call before any major financial changeA new job, a bonus structure change, a large purchase, a co-signed loan. Most can be handled if we know first.
- Document every large depositGift letter, sale receipt, transfer record. Cash deposits are the hardest to explain; avoid them.
- Get insurance quotes earlyEspecially on Lake waterfront, older St. Louis housing, and anything with a prior claim.
- Verify wiring instructions by phoneOn a number you already have, before every wire, every time.
Do not
- Open new credit or finance furniture and appliancesNew debt changes the debt-to-income ratio and can void the approval.
- Change jobs or become self-employedEven a better job resets income verification. Talk to us first.
- Move money between accounts without recordsEvery transfer needs a trail; unexplained transfers stall underwriting.
- Make large undocumented depositsCash, or money from a source that cannot be papered.
- Close accounts or pay off debt without askingSometimes it helps; sometimes it drains reserves the approval needed.
- Send sensitive documents by ordinary emailUse the encrypted portal. Never share your Social Security number over email or text.
Closing Disclosure, right of rescission, funds, and wire fraud
Three business days before signing
Federal rules require you to receive the Closing Disclosure at least three business days before consummation. Compare it to your Loan Estimate: rate, points, lender credits, projected payments, and cash to close. Certain changes (the APR moving past a tolerance, a product change, or a prepayment penalty being added) restart the three days. Small changes do not.
Refinances yes, purchases no
A purchase mortgage generally has no right to cancel after signing. Many non-purchase loans secured by your primary residence, including most refinances and home equity loans, carry a three-business-day right of rescission: you may cancel until midnight of the third business day after signing, receiving the disclosures, and receiving the rescission notice. The loan funds after that period. If you rescind a refinance, the original loan remains.
Follow the title company's verified process
Your cash to close is delivered the way the settlement company instructs, usually a wire or a cashier's check, sometimes with a limit on personal checks. Missouri and Kansas title companies each have their own approved-funds rules, so do not assume one method; confirm the amount and the method with the closer by phone, on a number you already had, the day before.
Never act on emailed wiring changes
Criminals watch real estate transactions and send convincing emails changing the wiring instructions at the last minute. Wiring instructions do not change. Before sending any wire, call the title company at a number from their website or a document you received in person, read the instructions back, and verify. If you receive a change by email or text, treat it as fraud until proven otherwise.
Who contacts you at each stage, and what DreamLux sends
| Stage | Who reaches out | What you receive | Typical timing |
|---|---|---|---|
| Goals and budget | Zach | A payment target and two or three program options | Same day |
| Pre-approval | Zach | Pre-approval letter, soft pull, secure portal invitation | Same business day on complete files |
| Application | Zach, then the lender's disclosure desk | Loan Estimate and disclosures for e-signature; lock confirmation | Within 3 business days of application |
| Documents and processing | Processor | A single list of what is still open, updated as items arrive | Days 1 to 10 after contract |
| Appraisal | Appraiser schedules access with the listing agent | The report, shared with you when received | Ordered day 1 to 3; back in 5 to 10 days |
| Underwriting | Zach | The conditional approval and the exact conditions | Days 10 to 18 |
| Clear to close | Zach and the title company | Clear to close, Closing Disclosure, signing appointment | Days 18 to 24 |
| Closing and funding | Title company closer; Zach present or on call | Signed documents, funding confirmation, keys after recording | Days 21 to 30; refinances plus the rescission period |
Timing is typical for a complete file and is not a promise. Appraisal availability, title issues, and document turnaround change it. Text updates go out at every stage; call or text (573) 301-4422 any time.
What to gather, by category
Programs vary; this covers a typical Missouri or Kansas file. The portal lists exactly what is open on yours.
Income, assets, and identity
- 30 days of pay stubsOr a year-to-date profit and loss if self-employed.
- Two years of W-2s or 1099sPlus two years of full tax returns for self-employed, commission, or rental income.
- Two months of bank statementsAll pages, including blank ones. Retirement and investment statements if used for reserves.
- Photo IDDriver's license or passport for every borrower.
- Employment contactHR or employer contact for verification; a signed contract for physician, relocation, or new-job files.
- ExplanationsLetters for large deposits, credit inquiries, gaps in employment, or name variations.
Transaction and program items
- Purchase contract and earnest money receiptWith all addenda and the agent's contact information.
- Homeowners insurance quote or declarationsA binder before closing; the declarations page on a refinance.
- Current mortgage statementRefinances; plus the HOA statement if applicable.
- VA Certificate of EligibilityWe can usually pull it; DD-214 or statement of service helps.
- USDA household incomeFor everyone in the home, whether or not they are on the loan.
- Gift letter and donor statementWhen any part of the down payment is a gift.
The words you will hear, defined
- Prequalification
- An estimate of what you may qualify for based on information you provide, before documents are verified.
- Pre-approval
- A lender-reviewed letter based on a credit pull and verified income and assets. The borrower is reviewed; the property is not; the loan is not yet approved.
- Application
- Complete when the lender has six items: name, income, Social Security number, property address, estimated value, and loan amount.
- Loan Estimate
- The three-page disclosure of rate, payments, costs, and cash to close, due within three business days of application. Not an approval.
- Rate lock
- A written commitment holding a rate for a set period. A quote is not a lock.
- Processing
- Verifying the file and ordering appraisal, title, and insurance before underwriting.
- Underwriting
- The lender's review of credit, capacity, capital, collateral, and program eligibility.
- Conditional approval
- Approval subject to listed conditions being satisfied.
- Appraisal
- A licensed appraiser's opinion of value and condition, ordered by the lender.
- Title
- The record of ownership and liens; a title commitment shows what must be cleared before closing.
- Closing Disclosure
- The five-page final statement of terms and costs, delivered at least three business days before consummation.
- Clear to close
- Underwriting's confirmation that all conditions are met and the loan can be signed.
- Consummation
- The moment you become contractually obligated on the loan, usually signing day.
- Right of rescission
- The three-business-day right to cancel certain non-purchase loans on your primary residence after signing.
- Funding
- The lender releases the money; on a purchase the deed and mortgage record the same or next day and keys follow.
- Escrow
- The account the servicer uses to pay taxes and insurance from part of each monthly payment.
Twenty milestones from the first call to keys
Print this page and check them off. The button prints only this checklist.
- First conversation: goals, budget, timeline, program priorities
- Soft-pull credit review
- Income and asset documents uploaded to the secure portal
- Verified pre-approval letter issued
- Offer accepted or refinance decision made
- Formal application complete (six items)
- Loan Estimate received and compared
- Rate locked in writing
- Homeowners insurance quote chosen
- Appraisal ordered and completed
- Title commitment received
- Conditional approval received
- All conditions satisfied
- Clear to close issued
- Closing Disclosure received (three business days before signing)
- Closing funds verified with the title company by phone
- Signing appointment completed
- Rescission period ended (refinances only)
- Loan funded and recorded
- Keys received; first payment date confirmed
How to start with DreamLux
- Text or call (573) 301-4422, or start onlineA ten-minute conversation about goals, budget, and timeline. No documents needed yet.
- Soft-pull pre-approval, same business dayCredit reviewed with a soft pull, documents through the secure portal, the file underwritten. The letter names the amount, the program, and the expiration.
- Shop with a written letter, then lock and closeOnce you are under contract, the eight steps above run on a calendar we share with you and your agent, with text updates at every stage.
Already in process somewhere else? Send me the loan estimate.
Wherever you are in the eight steps, the loan estimate tells me the rate, the points, the fees, and the cash to close, and I compare it against 280+ lenders the same day for free. If your current lender wins, I say so. If they do not, switching before the appraisal is usually painless.
Which loan programs does DreamLux offer in Missouri and Kansas?
Fourteen programs across 280+ wholesale lenders. If this page's program is not the right fit, the right one is a click away and the same soft-pull pre-approval carries over.
Where does DreamLux close loans?
Every county in Missouri and Kansas
Based in Columbia, licensed statewide in both states. Mid-Missouri, Lake of the Ozarks, Kansas City on both sides of the line, St. Louis, west-central Missouri, and Kansas from Wichita to Topeka to Lawrence, with a mobile notary at closing.
CountiesAll 114 Missouri counties and St. Louis City; all 105 Kansas counties
HoursMon to Fri 8am to 8pm CT · Sat and Sun 10am to 6pm CT
ContactLocal closing context across Missouri and Kansas
The eight steps are the same everywhere. A few things about closing differ by state and metro, and knowing them ahead of time removes surprises in the last week.
Columbia, Jefferson City, and Ashland
Closings run through local title companies with a settlement agent, and a mobile notary can bring the signing to your kitchen table in Boone, Cole, or Callaway County. Boone County reassesses in odd-numbered years, so the escrow set up at closing is estimated on the likely next bill. Mid-Missouri mortgage options cover the three markets.
Check my buying power in Mid-MissouriOsage Beach, Camdenton, Lake Ozark, Sunrise Beach, Laurie, and Gravois Mills
Dock permits, fire-district inspections, and waterfront insurance quotes go into processing early because they slow the file if they arrive late. Second-home and condo files add reserve and project review steps in underwriting. Lake of the Ozarks mortgage guidance is the hub.
Start a Lake purchase the right wayKansas City, Overland Park, Olathe, Lenexa, Raymore, Belton, and Gardner
Kansas closings on the Johnson County side and Missouri closings on the Jackson, Clay, and Cass County side use different recording fees and title customs, and Kansas foreclosure is judicial while Missouri's is non-judicial, which shows up in title review. Kansas repealed its mortgage registration tax in 2019, so neither side taxes the recording. Kansas City home financing covers both sides.
Run a Kansas City pre-approvalChesterfield, Creve Coeur, Ballwin, O'Fallon, Lake St. Louis, Kirkwood, Wildwood, Crestwood, The Grove, Tower Grove, and Lafayette Square
Municipal occupancy inspections in many St. Louis County cities and the City of St. Louis are a closing condition that belongs in processing, not the last week. Builder closings in St. Charles County often come with a preferred-lender credit to compare on the Loan Estimate. St. Louis mortgage options is the hub.
Compare a builder's process to oursLocal mortgage pages across Missouri and Kansas
The process is the same everywhere; the property, the taxes, and the programs around it are not. These pages carry the local detail.
Mid-Missouri
- Mid-Missouri
- Columbia, MO
- Jefferson City, MO
- Ashland, MO
- Fulton, Holts Summit and New Bloomfield
- Boonville, Pilot Grove and Prairie Home
- Taos, Wardsville and Osage Bend
- St. Martins, Lohman and Russellville
- California, Tipton and Jamestown
- Linn, Loose Creek and Osage County
- Moberly, Mexico and Sturgeon
- Sedalia, Warrensburg, Marshall and Clinton
Lake of the Ozarks
Kansas City metro
St. Louis metro
Statewide
Free tools for Missouri and Kansas buyers and owners
Everything here is free, and none of it requires a hard credit pull. Start with whichever matches where you are.
 SellFSBO PRO Listing ToolList for sale by owner on FSBO.com through our partner link. Buyers get pre-approved here.
DreamLux Home Loans is a DBA of NEXA Lending, LLC. NEXA Lending, LLC and FSBO.com share common ownership. See the Affiliated Business Arrangement disclosure below.
Send me your loan estimate. I will read it line by line.
Already have a quote from a bank, a credit union, or an online lender? Send the three-page Loan Estimate and I will walk you through what it actually says, where the cost lives, and whether our lender panel would price the same file differently. No credit pull, no application, no obligation.
What gets checked
- Section A origination charges
- Section C services you can shop for
- Lender credits and discount points
- Page 3 "In 5 Years" and Total Interest Percentage
What it is not
- Not a promise to beat it
- Not a credit pull
- Not a comparison of prepaids and escrows
- Not a rate quote
Search Missouri and Kansas homes
Get the pre-approval before the showing
Browse active listings across both states and save searches. The same soft-pull pre-approval carries to any of them.
Browse active listings and get introduced to an agent
Search every active Missouri and Kansas listing through our MLS home search and save the ones you like. Need an agent? We introduce you to a licensed partner agent in your market at no cost to you. Zach handles financing only; listing-side and negotiation work stays with the licensed agent.
For sale by owner
Buying or selling a FSBO home in Missouri or Kansas?
Zach Brown is a preferred mortgage partner for FSBO.com in Missouri and Kansas. Sellers list through our partner link; buyers show up with an underwritten pre-approval that a for-sale-by-owner seller can trust without an agent vetting it for them.
If you are selling
List on FSBO.com through our invite link and get $99 off the Plus or MLS plan. Your listing reaches the same buyer sites an agent's listing does, and buyers who call us get pre-approved before they tour your house.
Get My Invite LinkIf you are buying
A FSBO seller has no agent telling them your financing is real. Our pre-approval letter is underwritten first, names the program, and comes with a broker the seller can call. That is what gets a FSBO offer accepted.
Affiliated Business Arrangement Disclosure. DreamLux Home Loans is a DBA of NEXA Lending, LLC. NEXA Lending, LLC and FSBO.com share common ownership. Because of that relationship, referrals between the two may provide a financial or other benefit. You are not required to use FSBO.com to obtain mortgage financing from DreamLux Home Loans, and you are not required to use DreamLux Home Loans to list a property on FSBO.com.
Mortgage process questions
How long does the mortgage process take in Missouri and Kansas?
Most complete purchase files close in 21 to 30 days from an accepted contract. Refinances run a similar window plus the three-business-day rescission period before funding. The appraisal is the usual pacing item; a verified pre-approval done before the contract, and documents answered the same day, are what make the shorter end possible. Timing is typical, not a promise.
What is the difference between prequalification and pre-approval?
A prequalification is an estimate from what you tell us. A verified pre-approval uses a credit pull and reviewed income and asset documents, run through automated underwriting, so the letter reflects a lender's review of you as a borrower. Neither one means the loan is approved: the property has not been appraised and underwriting has not issued a decision. Sellers in Missouri and Kansas treat a verified pre-approval as a serious offer.
Does a pre-approval mean my loan is approved?
No. It means you, the borrower, have been reviewed. The loan is approved when an underwriter reviews the complete file including the property and issues a clear to close. A pre-approval also does not automatically make the loan close faster, although a complete file usually does.
When do I get the Loan Estimate?
Within three business days after the lender receives the six items that make an application: your name, income, Social Security number, the property address, an estimate of the property's value, and the loan amount. The Loan Estimate is a disclosure of terms and costs, not an approval.
How many times will my credit be pulled?
A soft pull for the pre-approval, which does not affect your score. A full credit report when the application is submitted to the lender. A soft refresh before closing to check for new debt. Multiple mortgage inquiries within a short shopping window are treated as one by the scoring models.
What is a rate lock and when should I lock?
A rate lock is a written commitment holding your rate for a set period, typically 30 to 60 days. A quote is not a lock. Most buyers lock once they are under contract and the Loan Estimate is in hand; the lock expiration goes on the calendar against the closing date.
What does the appraisal do, and what if it comes in low?
The lender's appraiser gives an opinion of value and condition. If the value comes in below the purchase price, the options are a price renegotiation, a larger down payment to keep the loan-to-value, a reconsideration of value with supporting sales, or, if the contract allows, walking away. Conventional appraisal waivers are possible on some strong files.
What are underwriting conditions?
Specific items the underwriter needs before final approval: an updated pay stub, a letter explaining a deposit, a title correction, insurance proof. Most files receive a conditional approval; clearing the conditions leads to the clear to close.
When do I receive the Closing Disclosure?
At least three business days before consummation, which is usually signing day. Compare it line by line to the Loan Estimate. Certain changes, such as the APR moving past a tolerance or a product change, restart the three days; most small changes do not.
Can I cancel after signing?
On a purchase, generally no. On most refinances and other non-purchase loans secured by your primary residence, you have until midnight of the third business day after signing, receiving the disclosures, and receiving the rescission notice to cancel. If you rescind a refinance, your original loan stays in place.
How much cash do I bring to closing, and how?
The Closing Disclosure states the cash to close. The title or settlement company tells you how to deliver it, usually a wire or a cashier's check, and each company has its own rules. Confirm the amount and the method by phone with the closer, on a number you already have, the day before. Never send a wire based on emailed instructions or an emailed change.
When is my first mortgage payment due?
Usually on the first of the second month after closing, because interest for the closing month is paid at closing. On a refinance the same rule applies from the funding date, which is why it can feel like you skip a payment.
What Missouri and Kansas homebuyers say
Reviews are collected and verified by Experience.com after closing. They are published as written by the borrower.
Individual results vary. Loan approval depends on credit, income, assets, property, and program guidelines. Reviews reflect the experience of the borrower named and are not a guarantee of any outcome.
Written by Zach Brown
The step people misunderstand most is the second one: a pre-approval letter reviews you, not the house, and it is not a closed loan. I say that on every call because a buyer who knows where they are in the process makes better decisions at every step after it. I built DreamLux in Columbia over two years as a wholesale broker with 280+ lenders, soft-pull pre-approvals, and a mobile notary for closings anywhere in Missouri or Kansas.
Before mortgages I spent about a decade in exercise physiology and sports nutrition. Measuring first and then prescribing is a habit that carried over.
Zach Brown
Wholesale pricing
DreamLux Home Loans wholesale mortgage rate quotes
Step one is a payment target, not a rate. Fill out the form below (no SSN, no credit pull) and you get the budget, the program options, and what the pre-approval will need, the same business day.
Rates subject to change. Not a commitment to lend. Quotes depend on credit, loan-to-value, property, occupancy, program, and lock period, and are provided by a licensed loan officer.
DreamLux Home LoansCheck My Buying Power
Tell us the purpose, the state, the price range, the down payment or equity, and your timeline. You get a payment target and the program options that fit, the same business day, before any application. No SSN, no credit pull.
Zach Brown | NMLS #2156538 | DreamLux Home Loans, a DBA of NEXA Lending, LLC | NMLS #1660690 | Equal Housing Lender | Licensed in Missouri & Kansas
Not a commitment to lend. All loans subject to credit approval, income and asset verification, appraisal and program guidelines.
Related local mortgage markets
DreamLux Home Loans is a DBA of NEXA Lending, LLC, NMLS #1660690. Every fact on this page can be checked against our official facts page and NMLS Consumer Access.
This is not a commitment to lend and not an advertisement of specific credit terms. All loans are subject to credit approval, property approval, and program guidelines that vary by lender and change without notice. Timelines are typical for complete files and are not promised. A pre-approval is not a loan approval; a Loan Estimate is a disclosure, not an approval. Descriptions of the Loan Estimate, Closing Disclosure, and right of rescission summarize federal rules in general terms; the disclosures you receive control. Closing procedures are described in general terms and are not legal advice; follow your title or settlement company's verified instructions.
Primary sources: CFPB, what information do I have to provide to receive a Loan Estimate · CFPB, Loan Estimate explainer · CFPB, Closing Disclosure explainer · CFPB, can I change my mind after I sign the loan closing documents · CFPB, how long do I have to rescind · CFPB, what is a prequalification versus a preapproval · CFPB, mortgage closing scams and wire fraud
NMLS Consumer Access: Zach Brown, NMLS #2156538 · NEXA Lending, LLC, NMLS #1660690 · Licensing and disclosures
Official entity reference
Verify DreamLux Home Loans Facts
Review official details for DreamLux Home Loans, Zach Brown NMLS #2156538, NEXA Lending, Missouri and Kansas mortgage services, loan programs, service areas, and contact information.