Kansas City, Missouri Luxury Financing | Kansas City, MO Luxury Jumbo Mortgage Guide

Jumbo mortgage guide for Sunset Hill, the Country Club District, Brookside, and Ward Parkway: loan math, older-home issues, and the Missouri side of the line.

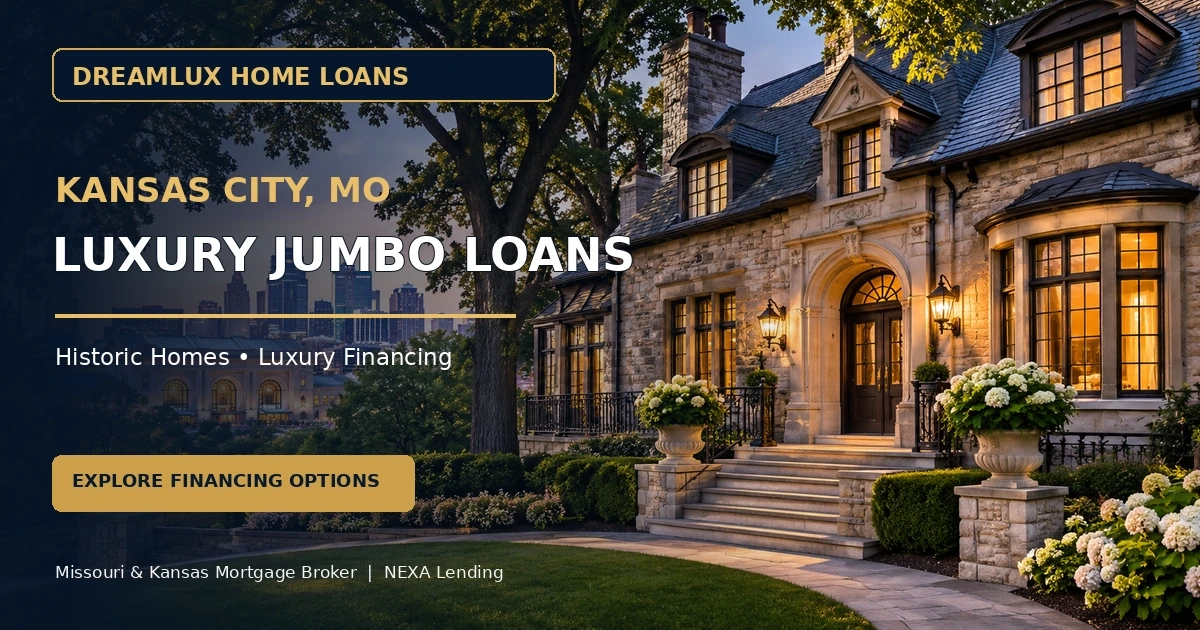
Historic home on Ward Parkway in Kansas City, Missouri

Kansas City, Missouri luxury financing

Kansas City, Missouri Luxury Jumbo Mortgage Guide

The Missouri side of Kansas City holds some of the metro's oldest high-value homes, from Sunset Hill to Ward Parkway. Financing them means planning for age, condition, and a state line that runs a few blocks west.

Five questions, about a minute. No Social Security number on the inquiry. Missouri files: Zach Brown or Scott Wilson. Zach is also licensed in Kansas.

Short answer

Is a jumbo loan in Kansas City, Missouri any different from one in Kansas?

The limit is the same and the license is not. Loans above $832,750 on a one-unit home are jumbo in Jackson, Clay, Platte, and Cass counties for 2026, the same figure as across the line in Johnson County. The property's state decides which license your loan officer needs. A $1,100,000 purchase in Kansas City, Missouri with 20 percent down is an $880,000 loan, a jumbo amount.

Old houses, modern underwriting

A 1920s home goes through 2020s loan review

Much of this part of the city was laid out in the early 1900s as the Country Club District, the planned community developed by J.C. Nichols that spans both sides of the state line. The homes are large, architect-designed, and often a century old.

For a lender, age raises practical questions. What is the condition of the roof, wiring, and plumbing? Can the home be insured at a reasonable premium? Are there recent sales of similar homes in similar condition? None of these is a barrier, and all of them are easier to answer before the contract than during it.

Kansas City, Missouri also levies a one percent earnings tax on residents and on people who work in the city. It does not change loan approval, but it belongs in a household budget when you compare addresses on either side of the line. Ask a tax adviser how it applies to you.

Either side of State Line Road

Comparing a Missouri address with a Kansas one

What changes when the house is on the other side of the line
ItemKansas City, MissouriJohnson County, Kansas
2026 one-unit conforming limit$832,750$832,750
DreamLux loan officerZach Brown or Scott WilsonZach Brown only
City earnings taxKansas City, MO levies one percent on residents and on those who work in the cityNo city earnings tax. Ask a tax adviser about state income tax differences
Typical housing stock at this priceEarly 1900s architect-built homesMix of historic estates in Mission Hills and newer homes farther south
Property tax and insuranceSet by parcel and policy. Get the actual tax bill and an insurance quote for each home you compare.

Looking on both sides? Read the Mission Hills estate guide and the Leawood jumbo guide. Zach Brown is licensed in both states and can quote either address.

Missouri-side neighborhoods

Four areas, and what a lender notices in each

All four are in Kansas City, Missouri. Mission Hills and Leawood, just across State Line Road, are Kansas cities with their own guides.

Sunset Hill

Part of the Country Club District on the Missouri side, near Loose Park, with large historic homes. Appraisers may need to reach across neighborhood lines for comparable sales.


Country Club District

The broader Nichols-planned area south of the Country Club Plaza. Homes associations and deed restrictions are common, so ask for association documents and dues.

Brookside

Older homes with a walkable shopping district. Prices span a wide range, so a loan here may be conforming or jumbo depending on the house and your down payment.

Ward Parkway

A boulevard of prominent residences running south from the Plaza. Unique homes on the parkway can be hard to compare, which makes the appraisal plan important.

Neighborhood notes describe financing considerations, not prices or values. Confirm boundaries, HOA rules, taxes, and school districts with your agent and the county.

Jumbo versus conforming

A $1,100,000 Kansas City, MO purchase, at five down payments

At this price the 25 percent row drops under the limit. A buyer near that line has a real choice between loan types.

Kansas City, Missouri example: a $1,100,000 purchase at five down payments
DownCash downLoan amountVersus the 2026 limit ($832,750)What to expect
5%$55,000$1,045,000JumboLimited. A small number of lenders, for strong borrower profiles.
10%$110,000$990,000JumboAvailable at select lenders, usually with strong credit and added reserves.
15%$165,000$935,000JumboCommonly available.
20%$220,000$880,000JumboThe standard jumbo down payment.
25%$275,000$825,000ConformingConforming loan amount. Private mortgage insurance usually applies under 20% down.

Arithmetic only: price minus down payment, before any financed fees. One-unit property. No interest rates are shown because pricing depends on the lender, the day, and your file. This is an illustration, not a loan offer or a statement of what you qualify for.

Jumbo or conforming? Check a loan amount

Enter a price and a down payment. The result compares the loan amount with the 2026 FHFA one-unit limit.

$880,000 loanTurn on JavaScript to change the numbers. The table beside this box shows the same math.

Educational estimate only. It does not check credit, income, assets, or the property, and it is not a qualification or a commitment to lend.

Limit source: FHFA set the 2026 baseline one-unit conforming loan limit at $832,750 (FHFA release, November 25, 2025). Checked November 20, 2026. FHFA had not published a 2027 limit when this page was written. Some lenders use higher early limits of their own, which are not official FHFA limits.

Have a Kansas City, Missouri address in mind?

Send it with your price range. We will flag the appraisal and insurance questions before you write the offer.

Before you write an offer

What to line up before bidding on an older Kansas City home

These items speed up an older-home file and protect you during the inspection period.

  • A homeowners insurance quote for the specific address, requested early
  • Inspection reports, including sewer line and electrical, as soon as you have them
  • Homes association documents and dues for the neighborhood
  • Income and asset documents for an underwritten pre-approval
  • A budget for near-term repairs, kept separate from your reserves

Comparing lenders

Renovation money changes the comparison

If you plan significant work, compare lenders on more than rate. A purchase loan with cash kept for renovation, a renovation loan, and a later cash-out refinance carry different costs and timelines. Ask for each to be laid out.

  • Ask each lender for a Loan Estimate on the same day, for the same loan amount and term.
  • Compare the interest rate and the APR together, then the origination charges in Section A.
  • Check whether points are being charged or a lender credit is being given.
  • Confirm the reserve requirement and the appraisal plan in writing.

The CFPB explains each line of the form in its Loan Estimate guide. DreamLux also offers a free loan estimate comparison.

Questions buyers ask

Kansas City, Missouri jumbo questions

What is the jumbo limit in Jackson County, Missouri?

$832,750 for a one-unit home in 2026, the same as Clay, Platte, and Cass counties and every other Missouri county.

Does the age of a Ward Parkway or Sunset Hill home affect loan approval?

Age alone does not. Condition does. The appraiser notes deferred maintenance and safety issues, and the home must be insurable. Significant issues may need repair before closing or a loan designed for renovation.

Will the Kansas City earnings tax affect my mortgage qualification?

Lenders qualify you on gross income and monthly debts, so the one percent city earnings tax is not part of the debt-to-income ratio. It does affect take-home pay, so include it in your own budget and ask a tax adviser about your situation.

Can Scott Wilson handle my loan if I end up buying in Kansas instead?

No. Scott is licensed in Missouri only. If your purchase moves to the Kansas side, Zach Brown, who is licensed in both states, originates the loan.

Can a Brookside home be financed with a conforming loan?

Often, yes. If the loan amount is $832,750 or less it is a conforming amount regardless of the neighborhood. The checker on this page shows where a given price and down payment land.

Are there historic district rules that affect financing?

Some Kansas City properties sit in local historic districts or have homes association restrictions that govern exterior changes. They do not usually affect loan approval, but they matter if you plan a renovation. Confirm the rules with the city and the association.

I am relocating to Kansas City. Where should I start?

With a pre-approval and a clear picture of both sides of the line. The relocating to Kansas City guide covers the move, and a purchase inquiry starts the loan side.

Who you work with

Missouri-licensed loan officers for Kansas City

Both originate loans on the Missouri side. Zach also covers the Kansas side.

Zach Brown, Senior Mortgage Loan Officer, DreamLux Home Loans

Zach Brown

Senior Mortgage Loan Officer · NMLS #2156538 · Licensed in Missouri and Kansas

Scott Wilson, Senior Mortgage Loan Officer, DreamLux Home Loans

Scott Wilson

Senior Mortgage Loan Officer · NMLS #2181239 · Licensed in Missouri only

Keep reading

Related Kansas City and Missouri resources

Next step

Start your Kansas City, Missouri inquiry

Buying or refinancing on the Missouri side? A Missouri-licensed loan officer reviews every inquiry.

  1. Send the purchase or refinance inquiry. It opens on our jumbo guide with the right form already selected.
  2. A licensed loan officer reviews it and replies with questions or lender options built on your numbers.
  3. If it fits, you complete the application and we start the underwritten pre-approval.

Prefer the full application? Start Application

Sources: FHFA: conforming loan limit values for 2026 · CFPB: what is a jumbo loan · CFPB: Loan Estimate explainer

Zach Brown | NMLS #2156538 | DreamLux Home Loans, a DBA of NEXA Lending, LLC | NMLS #1660690 | Equal Housing Lender | Licensed in Missouri & Kansas

All loans subject to approval; program availability, rates, terms, costs, and eligibility vary; not a commitment to lend. Mortgage examples on this page are educational and are not loan offers. Access to 280+ wholesale lenders; lender participation, program availability, pricing, and qualification vary.

Written by Zach Brown, NMLS #2156538. Conforming limit checked November 20, 2026.

Your DreamLux Home Loans team

Talk to a loan officer, not a call center

Two senior loan officers work your file through NEXA Lending's 280+ wholesale lenders. Reach either of us directly, or start one application and we'll take it from there.

Zach Brown
Zach Brown & Scott Wilson, DreamLux Home Loans

Not sure who to start with? Start one application or book a call. No credit impact to review your options.