St. Louis County Luxury Financing | St. Louis Luxury Jumbo Mortgage Guide

Jumbo mortgage guide for Ladue, Clayton, Frontenac, Huntleigh, Town and Country, and Chesterfield: loan math, appraisals, condos, and how to start an inquiry.

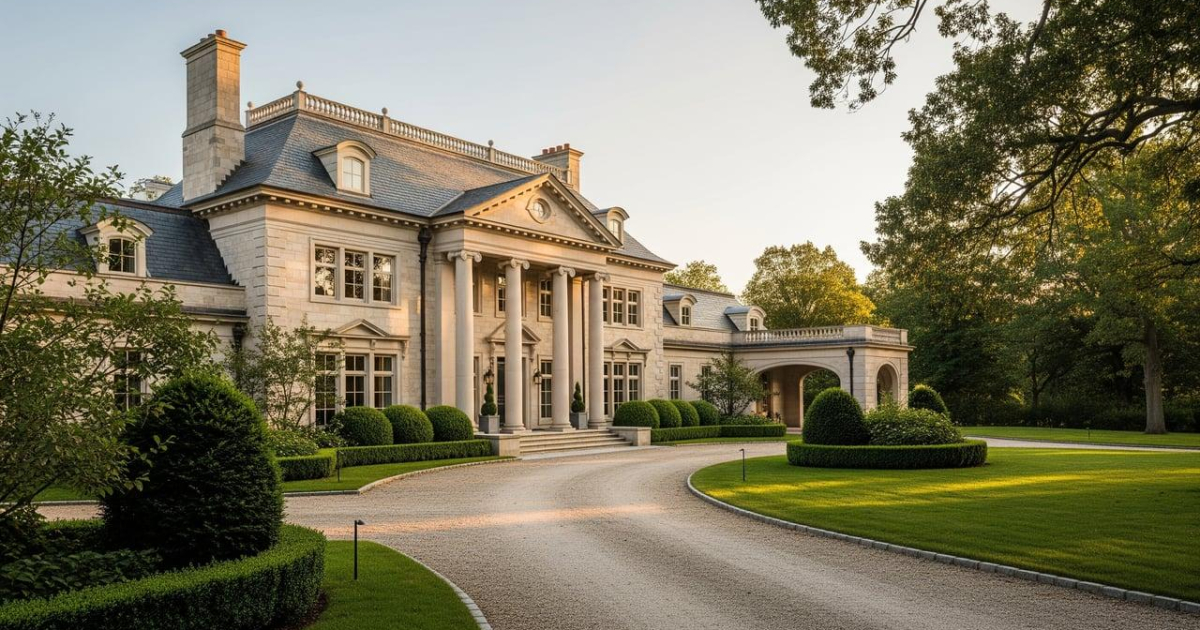
Estate home on a tree-lined street in St. Louis County, Missouri

St. Louis County luxury financing

St. Louis Luxury Jumbo Mortgage Guide

Ladue, Clayton, Frontenac, Huntleigh, Town and Country, and Chesterfield each put a different question to a jumbo lender. This guide walks through the ones that decide a St. Louis file: the appraisal, the condo project, and how the income is documented.

Five questions, about a minute. No Social Security number on the inquiry. Missouri files: Zach Brown or Scott Wilson. Zach is also licensed in Kansas.

Short answer

What makes a St. Louis luxury home loan a jumbo?

A loan amount above $832,750 on a one-unit home in 2026. St. Louis County, St. Louis City, and St. Charles County all use that baseline limit. A $1,500,000 purchase with 20 percent down is a $1,200,000 loan, well into jumbo territory. Above the limit there is no agency rulebook, so down payment, credit, reserve, and appraisal requirements are set lender by lender.

What is different here

In St. Louis the appraisal is often the hard part

Central St. Louis County is full of homes that do not resemble their neighbors: a 1920s estate on several acres beside a recent rebuild, or a full-floor condominium in a Clayton tower. Appraisers work from comparable sales, and here the comparables can be thin or far apart in age and style.

That matters on a jumbo loan because the lender bases the loan-to-value on the appraised value, not only the contract price. Many jumbo lenders also order a second appraisal above a set loan size. Planning for that before the offer, with the likely comparable sales in hand, avoids surprises during the contract period.

The county is also a patchwork of municipalities and school districts with different tax rates. The tax bill on the specific parcel belongs in your numbers from the start.

Municipality by municipality

Six St. Louis County markets and what each asks of a loan

All six are separate municipalities in St. Louis County. The notes below are about financing, not pricing.

Ladue

Large lots and a mix of original estates and new construction on teardown sites. Expect questions about lot value, recent rebuild sales, and whether a second appraisal applies at your loan size.


Clayton

The county seat, with single-family streets and high-rise condominiums near the business district. A condo purchase adds a project review: budget, reserves, owner-occupancy, and any litigation.

Frontenac

A small city of established homes on generous lots near Plaza Frontenac. Renovated and original-condition homes can sit side by side, so the appraiser's condition adjustments matter.

Huntleigh

One of the county's smallest cities, known for acreage estates. Few sales each year means comparable sales may come from neighboring cities, which is worth raising with the lender early.

Town and Country

Larger lots and many custom homes, some in private-street subdivisions. Ask for HOA or trustee assessment details, since they count in the housing payment.

Chesterfield

Newer luxury construction and golf communities farther west. More recent comparable sales generally make for a simpler appraisal, and builder contracts may be involved.

Neighborhood notes describe financing considerations, not prices or values. Confirm boundaries, HOA rules, taxes, and school districts with your agent and the county.

Estate appraisals

How to prepare for an appraisal on a one-of-a-kind St. Louis home

Before the offer

Ask your agent for the three to five most similar closed sales, even if they are in a neighboring city. If the list is short, tell your loan officer so the lender choice accounts for it.

During the contract

Give the appraiser a list of improvements with dates and costs: roof, mechanical systems, kitchen, additions. Appraisers can only credit what they know about.

If two appraisals are required

Lenders that require two generally lend on the lower value. Build time for both into your contract dates and keep a plan for a gap between value and price.

If the value comes in low

The options are a larger down payment, a renegotiated price, a reconsideration request with better comparables, or a different loan structure. None is automatic, so discuss them in advance.

Buying or refinancing in St. Louis County?

Send the address or price range. We will tell you what the appraisal and reserve picture looks like before you commit.

Jumbo versus conforming

A $1,500,000 St. Louis purchase, at five down payments

Every row is a jumbo loan amount. The differences are in how much cash you bring and which lenders will consider the file.

St. Louis example: a $1,500,000 purchase at five down payments
DownCash downLoan amountVersus the 2026 limit ($832,750)What to expect
5%$75,000$1,425,000JumboLimited. A small number of lenders, for strong borrower profiles.
10%$150,000$1,350,000JumboAvailable at select lenders, usually with strong credit and added reserves.
15%$225,000$1,275,000JumboCommonly available.
20%$300,000$1,200,000JumboThe standard jumbo down payment.
25%$375,000$1,125,000JumboOften asked for on larger loans, second homes, and investment property.

Arithmetic only: price minus down payment, before any financed fees. One-unit property. No interest rates are shown because pricing depends on the lender, the day, and your file. This is an illustration, not a loan offer or a statement of what you qualify for.

Jumbo or conforming? Check a loan amount

Enter a price and a down payment. The result compares the loan amount with the 2026 FHFA one-unit limit.

$1,200,000 loanTurn on JavaScript to change the numbers. The table beside this box shows the same math.

Educational estimate only. It does not check credit, income, assets, or the property, and it is not a qualification or a commitment to lend.

Limit source: FHFA set the 2026 baseline one-unit conforming loan limit at $832,750 (FHFA release, November 25, 2025). Checked November 20, 2026. FHFA had not published a 2027 limit when this page was written. Some lenders use higher early limits of their own, which are not official FHFA limits.

Before you write an offer

What to have ready for a St. Louis jumbo offer

A complete file lets the pre-approval be underwritten before you bid, which listing agents in these municipalities tend to expect.

  • Income documents for the last two years, including K-1s if you are a partner or owner
  • Asset statements covering the down payment and the reserves the lender will ask for
  • The current tax bill for the parcel and any subdivision or trustee assessments
  • Condo documents for a Clayton or Central West End building: budget, bylaws, insurance
  • A list of improvements if you are refinancing an older home

Comparing lenders

Bank relationship pricing versus a broker

St. Louis has private banks that discount jumbo rates for clients who move deposits or investments. That can be a good offer. Put it beside a brokered quote on the same day and compare the full cost, including what the relationship requires of you.

  • Ask each lender for a Loan Estimate on the same day, for the same loan amount and term.
  • Compare the interest rate and the APR together, then the origination charges in Section A.
  • Check whether points are being charged or a lender credit is being given.
  • Confirm the reserve requirement and the appraisal plan in writing.

The CFPB explains each line of the form in its Loan Estimate guide. DreamLux also offers a free loan estimate comparison.

Questions buyers ask

St. Louis jumbo mortgage questions

Is the jumbo limit different in St. Louis City and St. Louis County?

No. They are separate jurisdictions, but both use the 2026 baseline limit of $832,750 for a one-unit home, as does St. Charles County.

Do jumbo loans in Ladue or Huntleigh need two appraisals?

It depends on the lender and the loan size. Many jumbo lenders require a second appraisal above a threshold they set, often in the $1.5 million to $2 million range. Below it, one full appraisal with a review is typical.

Can I get a jumbo loan on a Clayton condominium?

Yes, when the building meets the lender's project standards. The lender reviews the association's budget, reserves, insurance, owner-occupancy, and any litigation. Buildings that fall outside standard guidelines need a lender with a program for them, usually with more down.

I am a partner at a St. Louis firm paid through a K-1. How is my income counted?

Most full-documentation jumbo lenders average two years of K-1 and personal return income and review the firm's returns if you own 25 percent or more. Some borrowers use bank statement programs instead. Which fits depends on your returns.

Can I refinance a St. Louis jumbo loan to take cash out?

Cash-out jumbo refinancing is available to eligible borrowers, with limits on loan-to-value that are tighter than for a rate-and-term refinance. A full appraisal is normally required. Start with the refinance overview or the refinance inquiry.

Do physicians at St. Louis hospitals need 20 percent down above the limit?

Not necessarily. Some lenders offer physician programs with lower down payments for eligible medical professionals, up to loan amounts each lender sets. Eligibility by degree and career stage varies.

Who are the DreamLux loan officers for St. Louis?

Zach Brown (NMLS #2156538) and Scott Wilson (NMLS #2181239). Both are licensed in Missouri. DreamLux is based in Columbia and works St. Louis files by phone, email, and secure upload, with a mobile notary at closing.

Who you work with

Missouri-licensed loan officers for St. Louis

Reach either of us directly. Both originate loans on St. Louis area properties.

Zach Brown, Senior Mortgage Loan Officer, DreamLux Home Loans

Zach Brown

Senior Mortgage Loan Officer · NMLS #2156538 · Licensed in Missouri and Kansas

Scott Wilson, Senior Mortgage Loan Officer, DreamLux Home Loans

Scott Wilson

Senior Mortgage Loan Officer · NMLS #2181239 · Licensed in Missouri only

Keep reading

Related St. Louis and Missouri resources

Next step

Start your St. Louis jumbo inquiry

Tell us whether you are buying or refinancing. A Missouri-licensed loan officer reviews it personally.

  1. Send the purchase or refinance inquiry. It opens on our jumbo guide with the right form already selected.
  2. A licensed loan officer reviews it and replies with questions or lender options built on your numbers.
  3. If it fits, you complete the application and we start the underwritten pre-approval.

Prefer the full application? Start Application

Sources: FHFA: conforming loan limit values for 2026 · CFPB: what is a jumbo loan · CFPB: Loan Estimate explainer

Zach Brown | NMLS #2156538 | DreamLux Home Loans, a DBA of NEXA Lending, LLC | NMLS #1660690 | Equal Housing Lender | Licensed in Missouri & Kansas

All loans subject to approval; program availability, rates, terms, costs, and eligibility vary; not a commitment to lend. Mortgage examples on this page are educational and are not loan offers. Access to 280+ wholesale lenders; lender participation, program availability, pricing, and qualification vary.

Written by Zach Brown, NMLS #2156538. Conforming limit checked November 20, 2026.

Your DreamLux Home Loans team

Talk to a loan officer, not a call center

Two senior loan officers work your file through NEXA Lending's 280+ wholesale lenders. Reach either of us directly, or start one application and we'll take it from there.

Zach Brown
Zach Brown & Scott Wilson, DreamLux Home Loans

Not sure who to start with? Start one application or book a call. No credit impact to review your options.