Columbia, MO Mortgage Lending Options | Brokers vs. Banks
If you are comparing mortgage lenders Columbia MO, the rate you see online is only one line in a much longer file. The real difference between a broker, bank, credit union and online lender often appears in underwriting flexibility, fees, turn times and how each handles your income profile. For borrowers who know the basics, that distinction matters whether you are buying a home near Columbia, refinancing in Central Missouri, or investing in rental property across Missouri and Kansas where licensing allows.
This guide gives you a clear comparison. You will start with the short answer on mortgage lenders Columbia MO, then review broker vs. bank vs. credit union vs. online lender options. You will learn why Columbia borrowers shop the broker channel, which purchase loan programs are most common, and how self-employed borrowers, investors and physicians qualify differently. We also cover refinance choices, what changes by location in Central Missouri, how to compare Loan Estimates line by line, what to verify before choosing a lender, FAQs and your next steps.
The Short Answer on Columbia Mortgage Lenders
When comparing mortgage lenders in Columbia, MO, borrowers really choose between four lender types: a mortgage broker, a community bank or credit union, a national retail bank, and an online or direct lender. That choice decides how many rate quotes you can see before you commit. A broker shops your file across a wholesale network; a bank or credit union generally prices only its own in-house programs. DreamLux Home Loans operates as a brokerage under NEXA Lending with access to a broad wholesale network, so one application can be compared against many pricing sheets instead of one. That structure is why Columbia buyers choose DreamLux Home Loans.
Program fit usually outweighs the advertised rate. Conventional, FHA, VA, USDA, jumbo, DSCR and bank statement loans each carry different credit, income and property rules. The cheapest option for a salaried buyer in Ashland may be the wrong lender for a self-employed buyer in Columbia.
Verify licensing before you share tax returns or bank statements. DreamLux Home Loan sis licensed in Missouri and Kansas only, led by Zach Brown, NMLS #2156538. Every lender you talk with should be verifiable on NMLS Consumer Access.
Use the rest of this page as a comparison framework: lender type first, then program fit, then Loan Estimate math, then pre-approval. The CFPB Loan Estimate explainer shows what each page is designed to reveal.
Broker vs. Bank vs. Credit Union vs. Online Lender in Columbia
These four lender types differ less in advertised rates than in how many lenders your file actually reaches.
Mortgage broker. One application reaches a wholesale network, so multiple pricing sheets appear side by side and broker compensation is separately itemised in your loan documents under federal originator rules. Best for non-textbook files: self-employment income, jumbo purchases, rental property.
Community bank or credit union. Local decision-making and relationship banking, usually limited to that institution’s own portfolio. Portfolio lending solves unusual cases, but your rate shopping stops at one lender.
National retail bank. Broad branch and app experience with standardized programs. Pricing follows a single set of investor guidelines and overlays, so credit or income outliers get declined rather than shopped.
Online or direct lender. Fast digital process and heavy marketing spend. Rates can be strong for simple, high-credit scenarios and less competitive once your file involves complexity, an unusual property type, or non-W-2 income.
| Lender type | Lenders accessed | Rate shop | Program breadth | Underwriting flexibility | Speed to close | Suits best |
|---|---|---|---|---|---|---|
| Broker | Many wholesale investors | Yes, side by side | FHA, VA, USDA, jumbo, DSCR | High; file can be re-shopped | Varies by investor | Self-employed, jumbo, investors |
| Community bank or credit union | One | No | Narrow, portfolio-based | Case-by-case | Moderate | Members with unusual cases |
| National retail bank | One | No | Standardized | Low; overlays decline outliers | Predictable | Simple W-2 files |
| Online or direct lender | One | No | Simple products | Low on complex files | Fastest on clean files | High-credit, straightforward purchases |
Treat these ratings as directional; breadth and speed vary by institution and loan type.
Boone County lender-level activity is accessible through the CFPB HMDA Data Browser, which shows actual lender activity in Columbia by year. Lenders exempt from HMDA reporting may be missing, so read those counts as a floor rather than a census.
Before picking a lender type, select your goal below so every quote you collect prices the same program. The next section covers why Columbia borrowers shop the broker channel.
Why Columbia Borrowers Shop the Broker Channel
Beyond the structural comparison above, here is how the broker channel produces different outcomes for Columbia-specific borrower profiles.
Wholesale pricing is the core difference. Brokers work from investor pricing sheets that are never posted publicly. The same borrower profile can be priced differently across investors because each one applies its own risk appetite, credit overlays and property rules. For a fuller breakdown of what that structure costs you, see Mortgage Broker vs. Bank: Which One Gets You a Better Deal?.
Program breadth matters just as much. Columbia mixes first-time buyers, university and healthcare employees, veterans and rural property owners. Those files land in different programs: FHA, VA, USDA, jumbo and bank statement. A broker routes each file to the lenders that actually do that loan type in volume, rather than forcing every borrower into one set of guidelines.
Jumbo and DSCR investors underwrite very differently from one another on reserves, rent coverage and property type. That is where shopping the file produces the widest gap in approval terms, not just in rate.
Broker compensation is separately itemised in your loan documents under federal originator rules (see 12 CFR § 1026.36). You can see what the broker is paid instead of assuming it is baked in.
Do not take a lender count on faith. Ask three questions: how many investors is the brokerage approved with for your specific program type, how many of those actively lend in Columbia, and who funds the loan at closing.
Answer those, and the next decision is program fit.
Purchase Loan Programs Columbia Buyers Compare Most
Program breadth only pays off when the program matches your income story. Six options drive most Columbia purchase comparisons.
- Conventional. The strongest fit for documented W-2 or salaried income, established credit and a down payment large enough to avoid mortgage insurance. It is also the usual path to the lowest advertised rates for well-qualified borrowers.
- FHA. Backed by HUD, FHA is commonly associated with more flexible qualification standards; confirm current credit, down payment and gift-fund rules on HUD’s FHA program pages. That combination keeps it among the most common choices for first-time buyers in Columbia and Ashland. FHA limits vary by county, so confirm the current figure for your county on FHA Mortgage Limits.
- VA. For eligible service members, veterans and surviving spouses. Most eligible borrowers can purchase with no down payment. This matters heavily around Fort Leonard Wood and Whiteman Air Force Base, and for the Truman VA community in Columbia. Veterans with full entitlement face no loan limit when the appraisal supports the price; VA loan limits explain how entitlement works.
- USDA. Built for eligible rural and small-town properties outside the Columbia city limits, including parts of Boone, Callaway and Cooper counties. Eligibility is drawn by area, not by county line, so check the USDA map for the specific address before you assume a property qualifies.
- Jumbo. Required once the loan amount exceeds the conforming loan limit for the property’s county, which is the deciding factor on higher-priced homes in Columbia, the Lake of the Ozarks and the Kansas City metro. FHFA publishes conforming loan limit values annually. Wholesale jumbo investors price and underwrite very differently from one another, which is where comparison shopping matters most.
- New construction. Construction-to-permanent loans and builder-preferred lender structures differ in draw schedules, inspection timing and closing costs. Always price a builder incentive against an outside lender quote to see the real total cost.
Your equity position from day one also determines what you can access later, so compare equity and refinance options while the purchase is still ahead of you.
Programs for Self-Employed Borrowers, Investors and Physicians
Beyond the purchase programs above, three borrower profiles need different qualification rules entirely: self-employed owners, rental investors and physicians.
Bank Statement and Self-Employed Loans
Business owners and 1099 earners whose write-offs shrink their taxable income often fail a conventional review even when cash flow is strong. Bank statement programs qualify borrowers on business deposits over a defined statement period, with exact requirements varying by investor, as well as on a profit and loss statement or asset depletion, so deposits and reserves carry the file instead of tax returns.
DSCR Loans for Rental Property
DSCR programs evaluate the property’s rental income relative to the mortgage payment rather than personal income, approval criteria vary by investor. That approach can carry a single rental or an entire portfolio across Missouri and Kansas, including owners who already hold several conventional mortgages.
Physician Loans
Physicians, dentists and residents often show large student loan balances next to income that has not caught up yet. Physician mortgage programs are designed to accommodate the income and debt profile common among medical professionals, terms vary by investor; request a program comparison for your situation.
Second Homes and Lake of the Ozarks Property
Waterfront, seasonal and short-term rental homes around the Lake of the Ozarks finance as second homes or as investor and DSCR loans where the lender permits rental use. Appraisal approach and flood zone review change the comparison more than the rate does.
Asset-Based and Alternative Jumbo
Borrowers with substantial reserves but irregular or complex income can qualify on assets rather than earnings. Wholesale investors set reserve requirements differently, so a file that does not fit one investor’s guidelines may fit another’s. Shopping those guidelines is where the outcome is decided.
That same comparison discipline carries into refinancing, where the loan type you already hold narrows the options.
Refinance Options Compared for Columbia Homeowners
For Columbia homeowners who already hold a mortgage, the same comparison logic applies in reverse: the goal is a better loan, not just a loan. Five refinance paths dominate local decisions, and each solves a different problem.
Rate-and-Term vs. Cash-Out
Rate-and-term refinance lowers your interest rate, your term, or both without taking cash out. It is a direct comparison against your current payment and remaining balance, so it fits when your credit or equity has improved since you closed. Cash-out refinance replaces the first mortgage with a larger loan and pays you the difference in cash. Columbia homeowners commonly use it for debt consolidation, renovations or major expenses. The tradeoff is a larger balance and a restarted term.
Streamline Options for FHA and VA Loans
FHA Streamline is a reduced-documentation refinance for an existing FHA loan. It often skips the appraisal, but the lender still has to document a net tangible benefit, so your rate or payment must improve. Cash back above $500 is not permitted. Missouri FHA borrowers weighing it against a full refinance can see the numbers in this FHA Streamline refinance vs. rate-and-term refi comparison. VA IRRRL, the Interest Rate Reduction Refinance Loan, works only on existing VA loans. It is designed to lower the rate and payment, and may involve reduced documentation requirements, confirm current VA IRRRL appraisal and credit requirements with your lender or at VA.gov. That streamlined process matters for veteran homeowners around Fort Leonard Wood and Whiteman Air Force Base.
HELOC or Cash-Out?
A HELOC leaves your first mortgage in place and adds a second lien. Compare total cost, draw period, repayment terms and whether a variable rate fits your budget before choosing it over cash-out. A HELOC preserves a low first-mortgage rate; cash-out replaces it.
Run the Break-Even Math First
Divide the total cost of the new loan by the monthly savings to see how many months it takes to come out ahead. Sell or refinance again before that point and the refinance costs you money.
What Changes by Location in Central Missouri
Location determines which lenders can actually close your loan, and program fit and investor appetite shift block by block across central Missouri.
Columbia mixes first-time buyers, university and healthcare employees, and relocating professionals. Price band usually decides the conventional versus jumbo question, and above the conforming limit, jumbo investors price and underwrite the same file very differently. That gap is why comparing Missouri mortgage rates today matters most in the jumbo band.
Ashland and Jefferson City are commuter-friendly towns where USDA eligibility often reaches outer edges, so verify the specific address on the USDA eligibility map before assuming any particular path.
Lake of the Ozarks tilts the comparison toward second homes, waterfront property, and rental or investor financing. Appraisal approach, flood zone review, and each lender’s appetite for short-term rental use all change which investors will consider the file at all.
Kansas City and St. Louis metros see more jumbo and physician loan activity, more condo and new construction inventory, and sharper differences between wholesale and retail pricing. DreamLux is licensed in Missouri and Kansas only, so every market above sits inside that footprint.
Veteran and military buyers drive steady VA purchase and IRRRL refinance demand near Fort Leonard Wood, Whiteman Air Force Base, and the Truman VA community in Columbia. VA documentation differs from a conventional file, so lenders that rarely close VA loans slow the process down.
Check the public record. The CFPB HMDA Data Browser lets you filter, aggregate, and download mortgage activity for Boone County rather than relying on marketing claims, showing which lender types are genuinely active before you shortlist anyone.
Once you know which mortgage lenders in Columbia, MO actually close loans in your area, the Loan Estimate is where the real comparison begins.
How to Compare Loan Estimates Line by Line
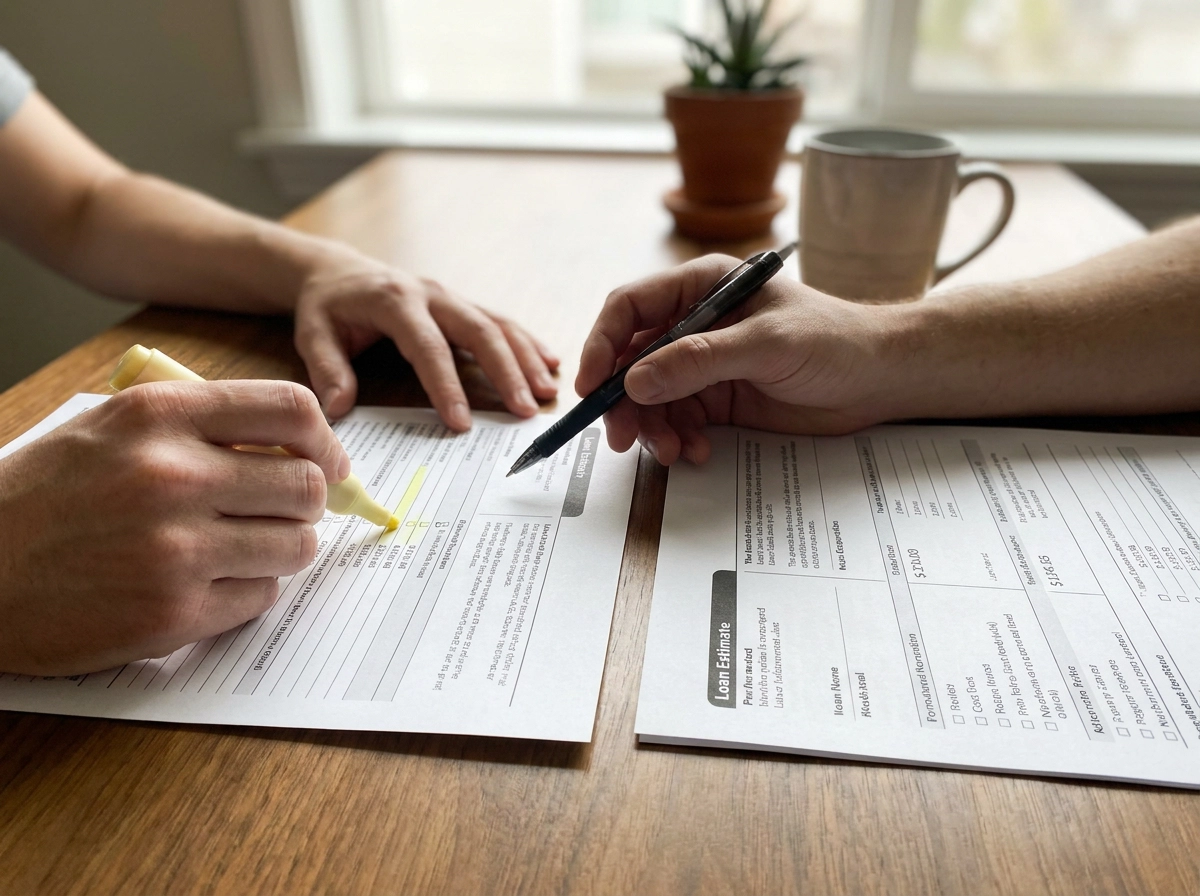
Location narrows which lenders can serve you. The Loan Estimate narrows which offer actually costs less. Every lender must use the same standardized form, and that standardization is the whole point: identical formatting across lenders lets you read offers line by line instead of page by page of marketing.
Page 1: rate, lock, and terms. Compare the interest rate, whether it is locked and for how long, and the loan terms. An unlocked quote is not the same offer as a locked rate, especially when your closing date is weeks away. A rate you cannot lock until 15 days before closing carries risk the locked offer does not.
Page 2: the costs behind the rate. Compare origination charges, discount points, services you cannot shop for and services you can shop for. Total lender costs, not the headline rate, determine what you actually pay at closing. Two lenders advertising the same rate can differ by thousands in points and fees.
Cash to close and five-year cost. Compare estimated cash to close and the total cost projection shown for the first five years. That projection captures closing costs you would not recover if you refinance or sell earlier than planned, which matters when your timeline in Columbia is shorter than the break-even point.
Credits versus points. Compare lender credits against discount points and how each changes your effective cost. Generally speaking, a lender credit lowers upfront closing costs in exchange for a higher interest rate, confirm the tradeoff on your specific Loan Estimate. Paying points does the opposite, trading upfront cost for a lower rate.
Make the offers comparable. Ask every lender to price the same loan amount, term, loan type and lock period. If the offers differ on any of those variables, you are comparing guesses, not loans. A second-opinion Loan Estimate comparison places your estimate beside multiple pricing sheets at once, so the gap shows up in dollars rather than in adjectives.
What to Verify Before You Pick a Columbia Mortgage Lender
Once you have two or three Loan Estimates side by side, the last step is verifying the lender behind them. A sharp estimate means little if the company cannot legally close your loan in Missouri.
Licensing Is Public Record
Look up every lender and loan officer on NMLS Consumer Access, the nationwide registry maintained by state regulators. DreamLux Home Loans operates under NEXA Lending and is led by Senior Mortgage Loan Officer and CEO Zach Brown, NMLS #2156538. Confirm that both the company and the individual officer hold active Missouri or Kansas licenses. DreamLux serves those two states only. A lender quoting you from outside that footprint may not be able to close in your market, no matter how good the rate looks.
Who Underwrites and Funds the Loan
Ask directly. A broker originates and packages your file; an investor funds it. The funding source tells you whose guidelines actually govern your approval, so you know whether you are dealing with one set of overlays or a wholesale network.
Disclosures and Plan B
Review the Loan Estimate and Closing Disclosure for broker compensation and disclosure timing, as described above. Federal mortgage disclosure rules under 12 CFR § 1026.19 require accurate and timely delivery of the Loan Estimate and Closing Disclosure. Disclosures that arrive late or change at the closing table are a warning sign.
Then ask what happens if your first approval falls apart. A lender with one set of guidelines sends you back to the start. Ask what happens if an approval falls through, a brokerage with multiple wholesale relationships may have more routing options than a single-investor lender. That fallback is often the difference between closing on time and losing the house.
Frequently Asked Questions About Columbia Mortgage Lenders
Licensing checks settle who can close your loan. Program fit decides what you actually pay. These are the questions Columbia borrowers ask most before they commit.
Which mortgage lender in Columbia, MO is best for first-time buyers?
There is no single best lender, only the best program fit. FHA is commonly associated with more flexible qualification standards for down payment and credit. Conventional wins on cost once your credit and down payment are strong. Price both before you commit.
Do I save money using a mortgage broker instead of my bank?
It depends on how complex your file is. A broker compares multiple wholesale pricing sheets while a bank offers one. The gap grows with self-employment income, jumbo loan amounts or investment property. For a simple W-2 file with strong credit, the difference can be modest.
Can self-employed borrowers in Columbia qualify without W-2 income?
Yes. Bank statement, profit-and-loss and asset-based programs exist specifically for business owners and 1099 earners whose tax returns understate real income. These programs qualify on business deposits over a defined statement period, with exact requirements varying by investor, and reserves and credit score driving the final terms.
Are VA loans available in Columbia and near Fort Leonard Wood?
Yes. VA purchase financing and VA IRRRL refinance are available to eligible service members, veterans and surviving spouses, including VA jumbo above the conforming loan limit. That covers borrowers around Fort Leonard Wood, Whiteman Air Force Base and the Truman VA community in Columbia.
Is DreamLux Home Loans licensed in Missouri?
Yes, in Missouri and Kansas only. Zach Brown holds NMLS #2156538 and the brokerage operates under NEXA Lending. Borrowers outside those two states cannot be served, so confirm your property sits inside the licensed footprint.
When do I need a jumbo loan instead of a conventional one?
When the loan amount exceeds the conforming loan limit for the property’s county. Jumbo investors set their own reserve, credit and appraisal rules, so offers differ more than they do on conventional loans. That variance is exactly where comparing multiple investors pays off.
Your Next Steps in the Columbia Mortgage Search
The FAQ answered program fit. Now turn answers into action.
Match the program to your income story first. W-2 borrowers should price conventional and FHA. Veterans should price VA. Self-employed borrowers should price bank statement options. Investors should price DSCR. Program fit decides which lender can approve you before rate shopping begins.
Then collect quotes on identical terms: same loan amount, term and lock period. Different terms make rates incomparable. Read both pages of every Loan Estimate as described above, and compare estimated cash to close and the five-year cost projection.
Verify licensing on NMLS Consumer Access and confirm the lender can close in Missouri or Kansas before you submit documents, as covered above.
Then get pre-approved with a written letter from a lender that can see more than one pricing sheet. A single-lender pre-approval reflects one set of guidelines. A brokerage can compare several before you commit. DreamLux Home Loans serves Columbia, Ashland, Jefferson City, the Lake of the Ozarks, Kansas City and St. Louis. Pre-approval is the fastest way to see real numbers instead of estimates. Start there, then compare offers line by line.
Conclusion
Choosing a Columbia, MO mortgage lender is less about picking a big name and more about finding the right program and transparent pricing. A broker can shop more pricing sheets and uncover options single-lender approvals miss. DreamLux Home Loans, operating under NEXA Lending and led by Zach Brown, NMLS #2156538, is licensed in Missouri and Kansas only. Ready to turn estimates into real numbers? Get your written pre-approval, then compare offers line by line. Your Columbia home search deserves a lender who works as hard as you do.








 Zach Brown | NMLS #2156538 | DreamLux Home Loans, a DBA of NEXA Lending, LLC | NMLS #1660690 | Equal Housing Lender | Licensed in Missouri & Kansas