Columbia, MO Mortgage Broker: Compare Home Loan Programs, Rates & Costs
By Zach Brown | Senior Mortgage Loan Officer | NMLS #2156538
DreamLux Home Loans | DBA NEXA Lending, LLC | NMLS #1660690
Published November 17, 2026
Buying a home in Columbia, Missouri?
Whether you’re a first-time homebuyer, relocating to Mid-Missouri, purchasing a higher-value property, building a custom home, or refinancing, your mortgage options shouldn’t be limited to a single lender.
At DreamLux Home Loans, we help qualified homebuyers, homeowners, and real estate investors explore financing through a network of 280+ wholesale lenders.
Our goal is to help you compare mortgage rates, closing costs, monthly payments, program requirements, and long-term financing considerations so you can make an informed decision.
Serving Columbia, Ashland, Jefferson City, Fulton, Boonville, and surrounding Mid-Missouri communities, with mortgage services available in Missouri and Kansas.
Ready to explore your options?
Start Your Secure Mortgage Application | Schedule a Mortgage Consultation
What Does a Mortgage Broker in Columbia, MO Do?
A mortgage broker helps borrowers compare available mortgage financing from multiple lenders rather than relying exclusively on one bank’s loan products.
For example, one lender might offer competitive conventional financing, while another may have different eligibility requirements or pricing for physician, construction, jumbo, or self-employed borrowers.
A comprehensive mortgage comparison considers:
- Interest rate and annual percentage rate (APR)
- Estimated monthly principal and interest
- Property taxes and homeowners insurance
- Mortgage insurance, when applicable
- Lender fees, discount points, and closing costs
- Down payment and estimated cash needed at closing
- Loan eligibility and longer-term financing goals
The Consumer Financial Protection Bureau recommends comparing Loan Estimates when evaluating mortgage offers.
Official resource: CFPB — Loan Estimate Explained
Conventional Mortgage Loans in Columbia, Missouri
Conventional mortgages are popular among first-time homebuyers, repeat buyers, and homeowners seeking to refinance.
Some eligible conventional programs allow down payments as low as 3%, depending on borrower qualifications and program requirements.
Conventional financing may be appropriate for borrowers with qualifying credit, income, assets, and debt-to-income ratios.
Private mortgage insurance may apply when the down payment is below 20%, and certain cancellation rules can differ from FHA mortgage insurance requirements.
For Columbia-area buyers, comparing conventional financing with FHA or other eligible programs can help clarify the complete cost of financing.
Helpful resource: Fannie Mae — HomeReady Mortgage
FHA Home Loans in Columbia, MO
FHA-insured mortgages can provide an alternative financing path for eligible buyers, including some borrowers who may not meet certain conventional underwriting requirements.
Qualified borrowers may be eligible for a down payment as low as 3.5%.
FHA loans generally include upfront and annual mortgage insurance premiums, so buyers should compare total monthly payments and estimated closing costs rather than evaluating the interest rate alone.
Official resource: HUD — Buying a Home
VA Mortgage Loans for Columbia and Jefferson City Veterans
Eligible veterans, active-duty service members, and certain surviving spouses may qualify for VA-backed mortgage benefits.
Depending on the transaction and eligibility, VA purchase financing may offer:
- No required down payment
- No monthly mortgage insurance
- Competitive lender financing options
- Purchase and eligible refinancing opportunities
A VA funding fee may apply unless the borrower qualifies for an exemption.
Eligibility is determined under VA requirements, and borrowers must also meet applicable lender and underwriting standards.
Official resource: U.S. Department of Veterans Affairs — VA Purchase Loans
USDA Home Loans Near Columbia and Ashland, Missouri
USDA Rural Development financing may provide eligible homebuyers with a no-down-payment option for qualifying primary residences.
However, eligibility depends on several factors:
- Exact property address
- Household income
- Primary-residence occupancy
- Credit and repayment qualifications
- Applicable program requirements
Not every home in Boone County, Ashland, or the Columbia area qualifies.
Before making an offer, verify the property’s eligibility rather than assuming a location qualifies based on its city or ZIP code.
Official resource: USDA Property and Income Eligibility
Physician Mortgage Loans in Columbia, Missouri
Columbia has a significant healthcare community, including medical professionals working with University of Missouri Health Care and other regional employers.
Some mortgage lenders offer specialized financing for qualifying physicians, residents, fellows, and certain other medical professionals.
Depending on the program, physician mortgage financing may provide alternative treatment of student loans, employment contracts, mortgage insurance, or down-payment requirements.
These features vary by lender and are not guaranteed.
A comparison against conventional and jumbo financing can help determine which available structure better fits the borrower’s circumstances.
Jumbo Mortgage Loans for Higher-Value Columbia Homes
Jumbo mortgages are generally used when financing exceeds applicable conforming loan limits.
Because jumbo loans are not subject to the same standardized purchase requirements as conforming loans, eligibility and pricing may vary significantly between lenders.
Buyers purchasing higher-value properties in Columbia and surrounding Mid-Missouri communities may benefit from comparing multiple jumbo loan programs.
Important considerations include credit requirements, down payment, reserves, debt-to-income limits, and property eligibility.
Construction Loans in Columbia and Mid-Missouri
Building a home introduces financing considerations beyond a traditional purchase mortgage.
Construction financing may involve:
- One-time-close construction-to-permanent loans
- Two-close construction financing
- Construction draws and inspections
- Builder approval requirements
- Lot equity and down-payment calculations
- Interest-only payments during construction, when applicable
The right structure depends on the project, builder, land ownership, borrower qualifications, and lender guidelines.
DSCR Investor Loans and Self-Employed Mortgage Options
Some real estate investors may qualify for Debt Service Coverage Ratio (DSCR) financing based on eligible property cash flow rather than traditional personal-income underwriting.
DSCR programs can vary in their treatment of rental income, property type, reserves, short-term rentals, and required coverage ratios.
For qualifying self-employed borrowers, bank statement or alternative-documentation mortgage programs may also be available.
These programs generally have different eligibility requirements, pricing, and documentation standards than conventional financing.
Why Compare Mortgage Rates, APR and Closing Costs?
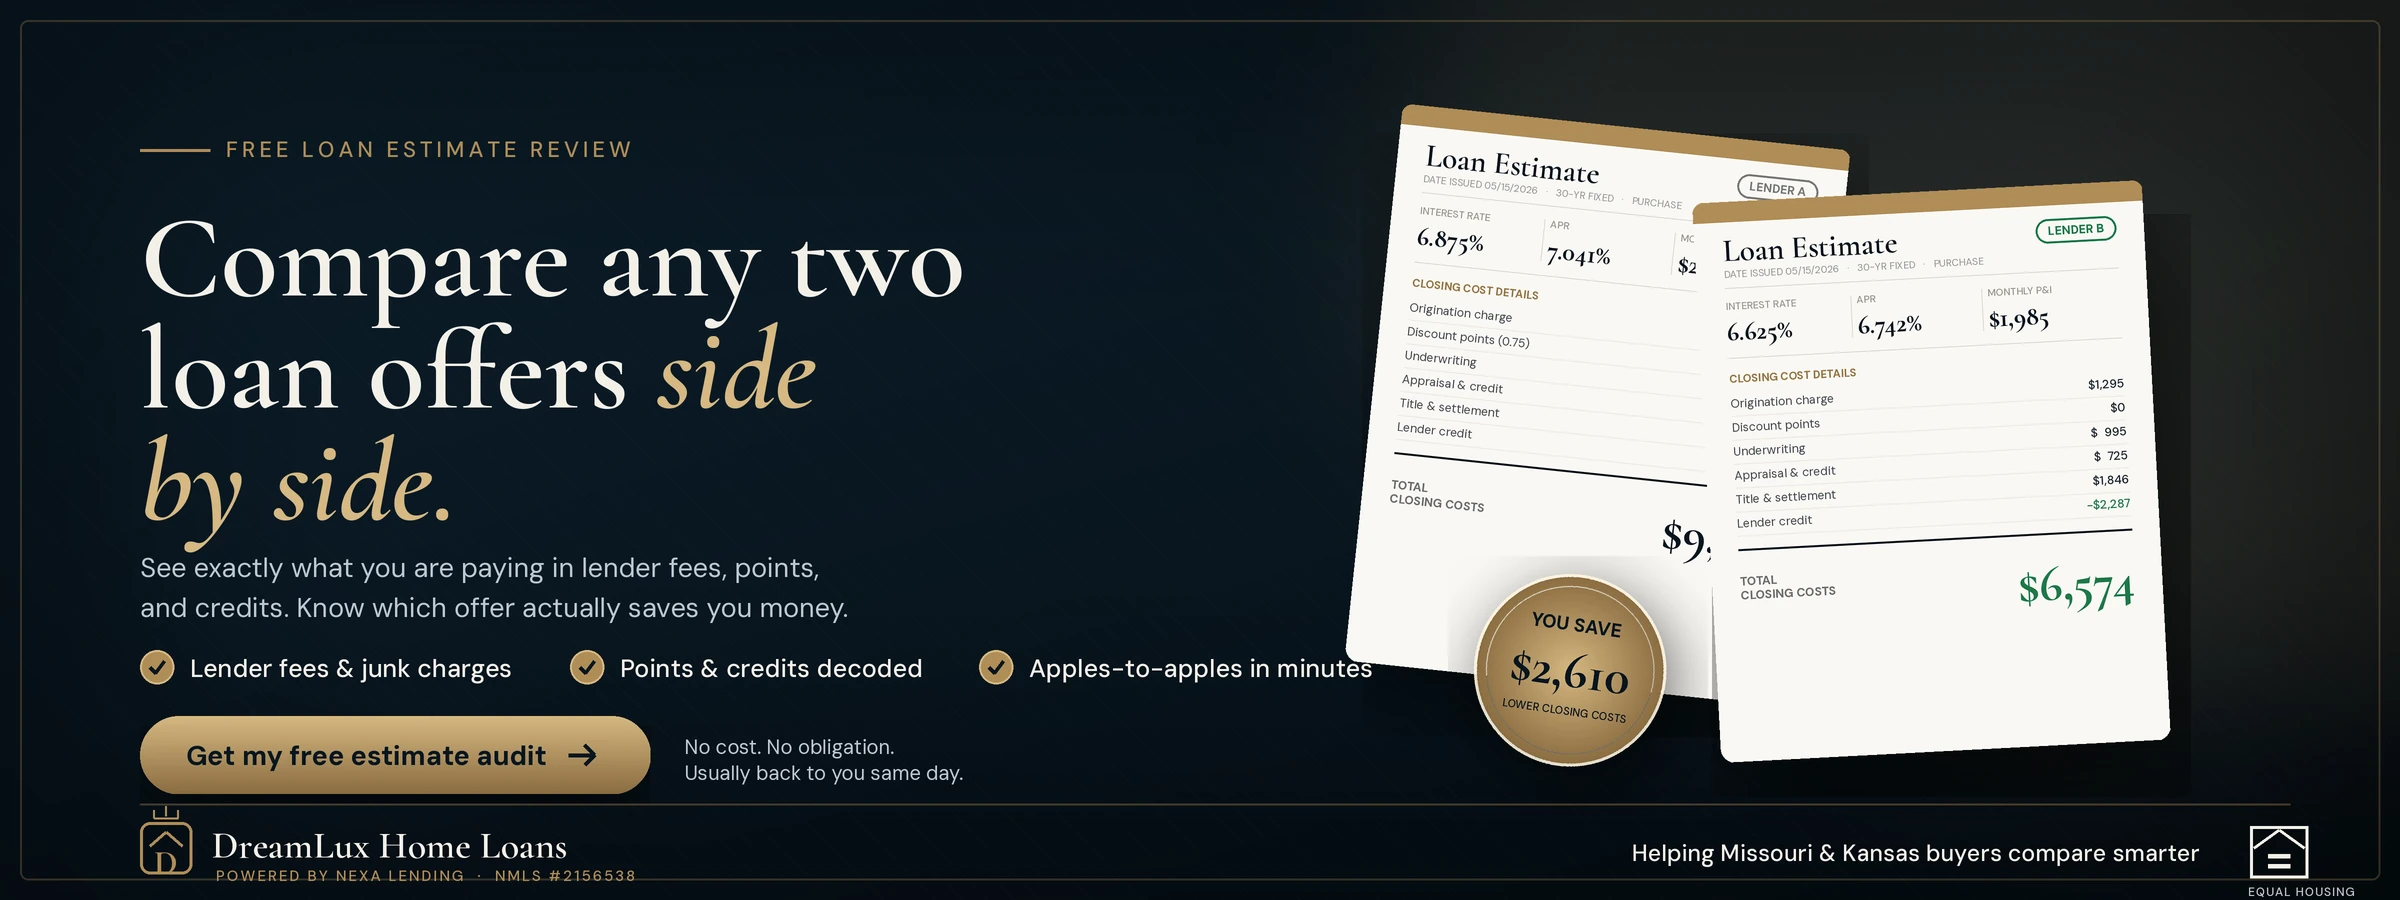
The lowest advertised interest rate does not necessarily represent the lowest overall mortgage cost.
For example, one lender may offer a lower rate in exchange for additional discount points, while another may offer a slightly higher rate with lower upfront charges.
A useful mortgage comparison considers:
- Estimated monthly payment
- APR and financed costs
- Cash required at closing
- Mortgage insurance
- Expected time in the home or mortgage
- Potential refinancing considerations
Refinancing is never guaranteed and depends on future market conditions, property value, credit, income, and program eligibility.
Official resource: CFPB — Compare Loan Offers
Why Work With DreamLux Home Loans?
DreamLux Home Loans focuses on helping borrowers understand their available mortgage choices rather than assuming one loan program fits everyone.
Our approach emphasizes:
- Access to a broad wholesale lending network
- Comparison of eligible mortgage programs
- Clear explanations of rates, costs, and payments
- Guidance for conventional and specialty financing
- Local familiarity with Columbia and Mid-Missouri
- Personalized communication throughout the mortgage process
We believe borrowers deserve to understand the numbers behind one of their largest financial decisions.
Frequently Asked Questions About Columbia, Missouri Mortgages:
Who is the best mortgage lender in Columbia, MO?
The best mortgage lender depends on your credit, income, loan amount, property, available programs, and financing goals. Comparing multiple eligible loan offers can help identify competitive options for your circumstances.
Do I need 20% down to buy a home in Columbia?
No. Some qualifying conventional programs allow as little as 3% down, FHA may allow 3.5%, and eligible VA or USDA borrowers may qualify for no-down-payment financing.
Can first-time homebuyers qualify for mortgage assistance in Missouri?
Potentially. Eligible buyers may qualify for certain Missouri Housing Development Commission programs or other available assistance, subject to income, purchase-price, funding, and program requirements.
Official resource: Missouri Housing Development Commission
Are USDA loans available near Columbia, Missouri?
Some properties in surrounding areas may qualify, but eligibility must be verified using the exact address and applicable household-income requirements.
Are physician mortgages available in Columbia?
Potentially. Specialized mortgage programs may be available to qualifying physicians, residents, fellows, and certain other medical professionals. Requirements vary by lender.
Can self-employed borrowers qualify for a mortgage?
Yes, subject to qualifications. Depending on the borrower’s financial circumstances, conventional documentation or alternative bank statement programs may be available.
Can I finance a new construction home in Mid-Missouri?
Potentially. Construction financing is available through certain lenders, subject to project approval, builder requirements, property eligibility, and borrower qualifications.
Can investors qualify using rental-property income?
Some DSCR mortgage programs evaluate eligible rental-property cash flow. Qualification depends on the property’s financial performance and the lender’s specific underwriting requirements.
Is a mortgage broker different from a bank?
Yes. A bank generally offers its own mortgage products, while a mortgage broker can help borrowers compare financing available from multiple participating lenders.
Should I get preapproved before making an offer?
Preapproval can help clarify your estimated purchasing budget and financing options before you submit an offer. It is not a final loan approval or guarantee of financing.
About the Author:
Zach Brown, Senior Mortgage Loan Officer | NMLS #2156538
Zach Brown is a mortgage loan officer with DreamLux Home Loans, DBA NEXA Lending, LLC (NMLS #1660690) statewide across Missouri & Kansas.
Based in Mid-Missouri, Zach assists homebuyers, homeowners, and real estate investors with mortgage financing, including Conventional, FHA, VA, USDA, Physician, Jumbo, Construction, DSCR, and alternative-documentation loan programs.
His approach focuses on personalized mortgage comparisons, borrower education, and helping clients understand the financing options available for their individual goals.
Professional profile: Zach Brown — MortgageMatchup
Verify licensing: NMLS Consumer Access
DreamLux Home Loans Mortgage Team:
Scott Wilson, Senior Mortgage Loan Officer| NMLS #2181239:
-
Scott Wilson is part of the DreamLux Home Loans mortgage team, helping borrowers across Missouri Statewide explore mortgage financing options and understand the home loan process.
Individual state licensing and authorizations should be verified through NMLS Consumer Access.
Zach Brown, Senior Mortgage Loan Officer | NMLS #2156538:
-
Zach Brown is a mortgage loan officer with DreamLux Home Loans, DBA NEXA Lending, LLC (NMLS #1660690) statewide across Missouri & Kansas.
Sources and Further Reading:
- Consumer Financial Protection Bureau — Loan Estimate
- Consumer Financial Protection Bureau — Compare Loan Offers
- U.S. Department of Housing and Urban Development
- U.S. Department of Veterans Affairs — VA Purchase Loans
- USDA Rural Development — Property and Income Eligibility
- Missouri Housing Development Commission
- NMLS Consumer Access
Compare Your Columbia Mortgage Options Today:
Whether you’re buying your first home, building, refinancing, relocating, or investing in Columbia and surrounding Mid-Missouri communities, DreamLux Home Loans can help you explore your available financing options.
Start Your Secure Mortgage Application
Schedule a Mortgage Consultation
Visit DreamLux Home Loans
DreamLux Home Loans | DBA of NEXA Lending, LLC | NMLS #1660690 | Equal Housing Lender.
All loans subject to credit approval, underwriting, property eligibility, and applicable program requirements. Interest rates, terms, fees, and financing availability vary.








 Zach Brown | NMLS #2156538 | DreamLux Home Loans, a DBA of NEXA Lending, LLC | NMLS #1660690 | Equal Housing Lender | Licensed in Missouri & Kansas