Mortgage Pre-Approval in Missouri and Kansas: How to Get Approved, What Lenders Verify and How Long It Lasts

A mortgage pre-approval is the difference between hoping a seller takes you seriously and being able to prove you can close. In Missouri and Kansas, where the same house often draws several offers in the first weekend, the buyer holding a verified pre-approval is the one the listing agent calls back first. This guide explains what pre-approval is, how it differs from pre-qualification, what you need to supply, how long it lasts, and how to compare offers from more than one lender without hurting your credit.
What a Mortgage Pre-Approval Actually Is
A pre-approval is a lender’s written decision, based on documents you have submitted, that you qualify for a specific loan amount under a specific program. It goes further than a pre-qualification, which is typically a quick estimate from stated income and a soft credit check.
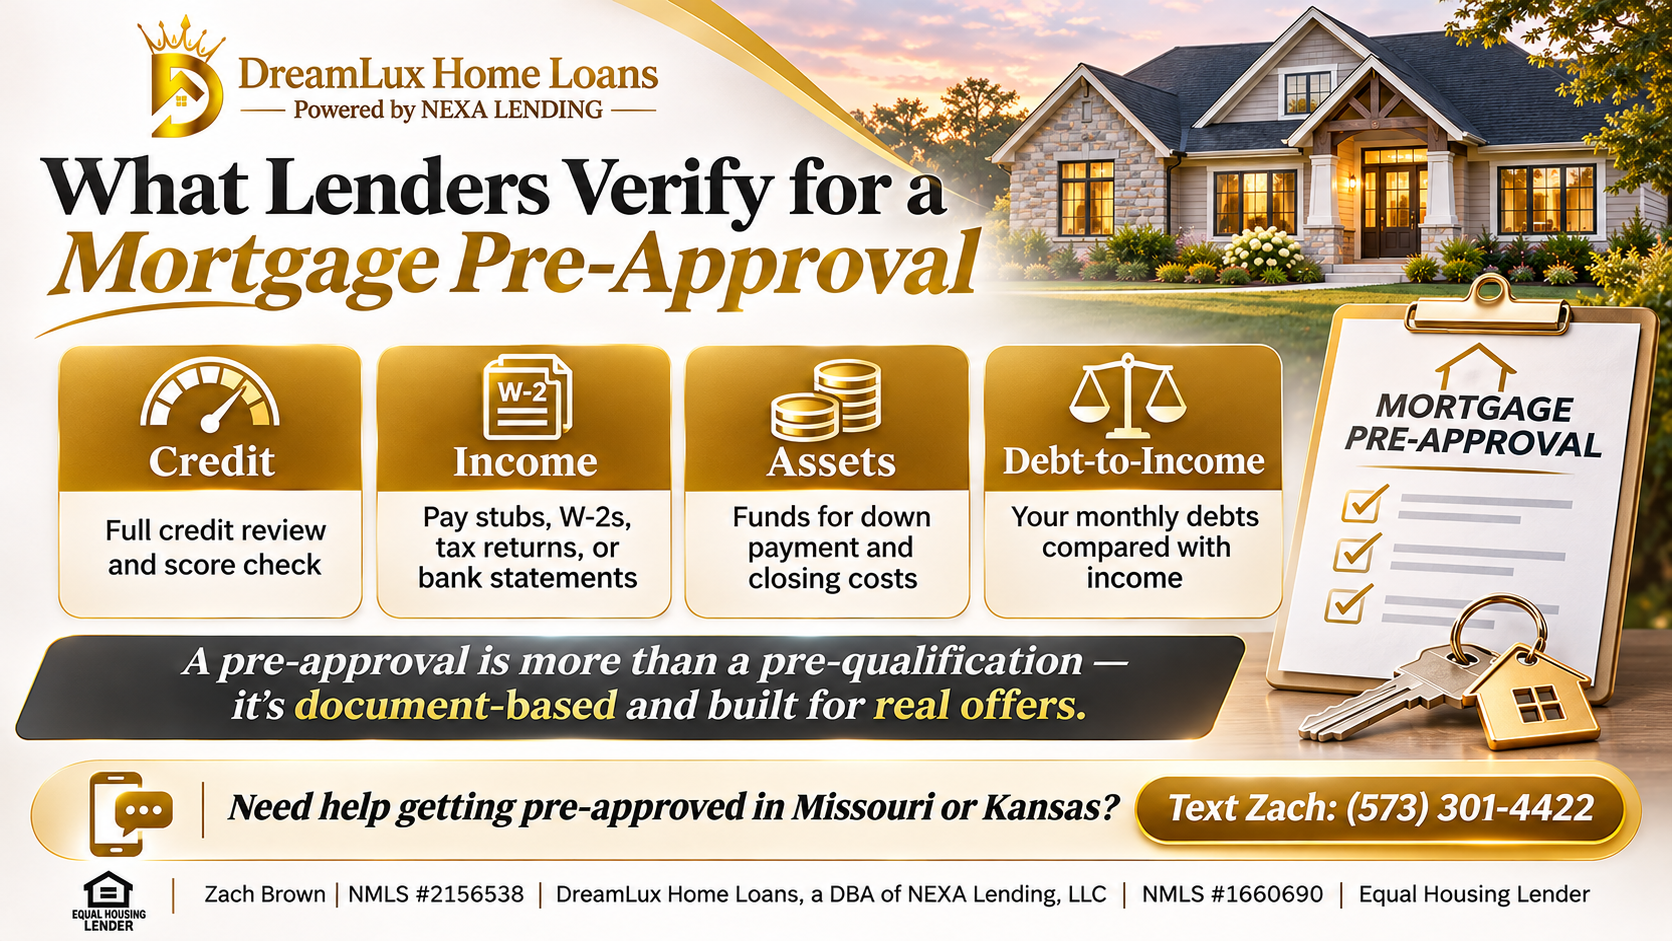
A pre-approval generally involves:
- A full credit pull and review of your credit report
- Income verification through pay stubs, W-2s, tax returns or bank statements
- Asset verification for down payment and closing costs
- A check of your debt-to-income ratio against the specific loan program’s guidelines
That document is what you hand a real estate agent in Columbia, Kansas City, St. Louis or the Lake of the Ozarks when you make an offer.
Pre-Approval vs. Pre-Qualification: Why the Difference Matters
Pre-qualification answers “roughly what could I borrow?” Pre-approval answers “what will a lender commit to lend me, and on what terms?” Sellers and listing agents in Missouri and Kansas treat them very differently, and some sellers’ agents will not forward an offer to their client without a verified pre-approval letter attached.
Pre-qualification is useful for early planning. It is not a substitute for pre-approval once you are seriously touring homes.
How the Pre-Approval Process Works, Step by Step
- Initial conversation. You talk through goals, timeline, credit picture and down payment. This is where the loan program gets chosen.
- Document collection. Income, asset, identity and, where relevant, gift or business documentation.
- Underwriting review. A pre-approval done properly is reviewed by underwriting, not just run through an automated engine.
- Pre-approval letter issued. The letter states your maximum purchase price, loan amount, program and expiration.
If you want the complete document list laid out in one place, our mortgage pre-approval checklist walks through it item by item.
What You Need to Get Pre-Approved in Missouri or Kansas
Most borrowers should be ready to provide:
- Government-issued ID and Social Security number
- Last 30 days of pay stubs and two years of W-2s, or two years of tax returns if self-employed
- Two months of bank and investment statements
- Explanation of any large or unusual deposits
- Rental income documentation if you own investment property
- For VA loans, your Certificate of Eligibility; for FHA, nothing extra at this stage
Self-employed buyers, 1099 earners and business owners often qualify on more than tax returns alone. Bank statement and self-employed loan programs let deposits and profit-and-loss statements show real income that tax returns understate.
How Long Is a Mortgage Pre-Approval Good For?
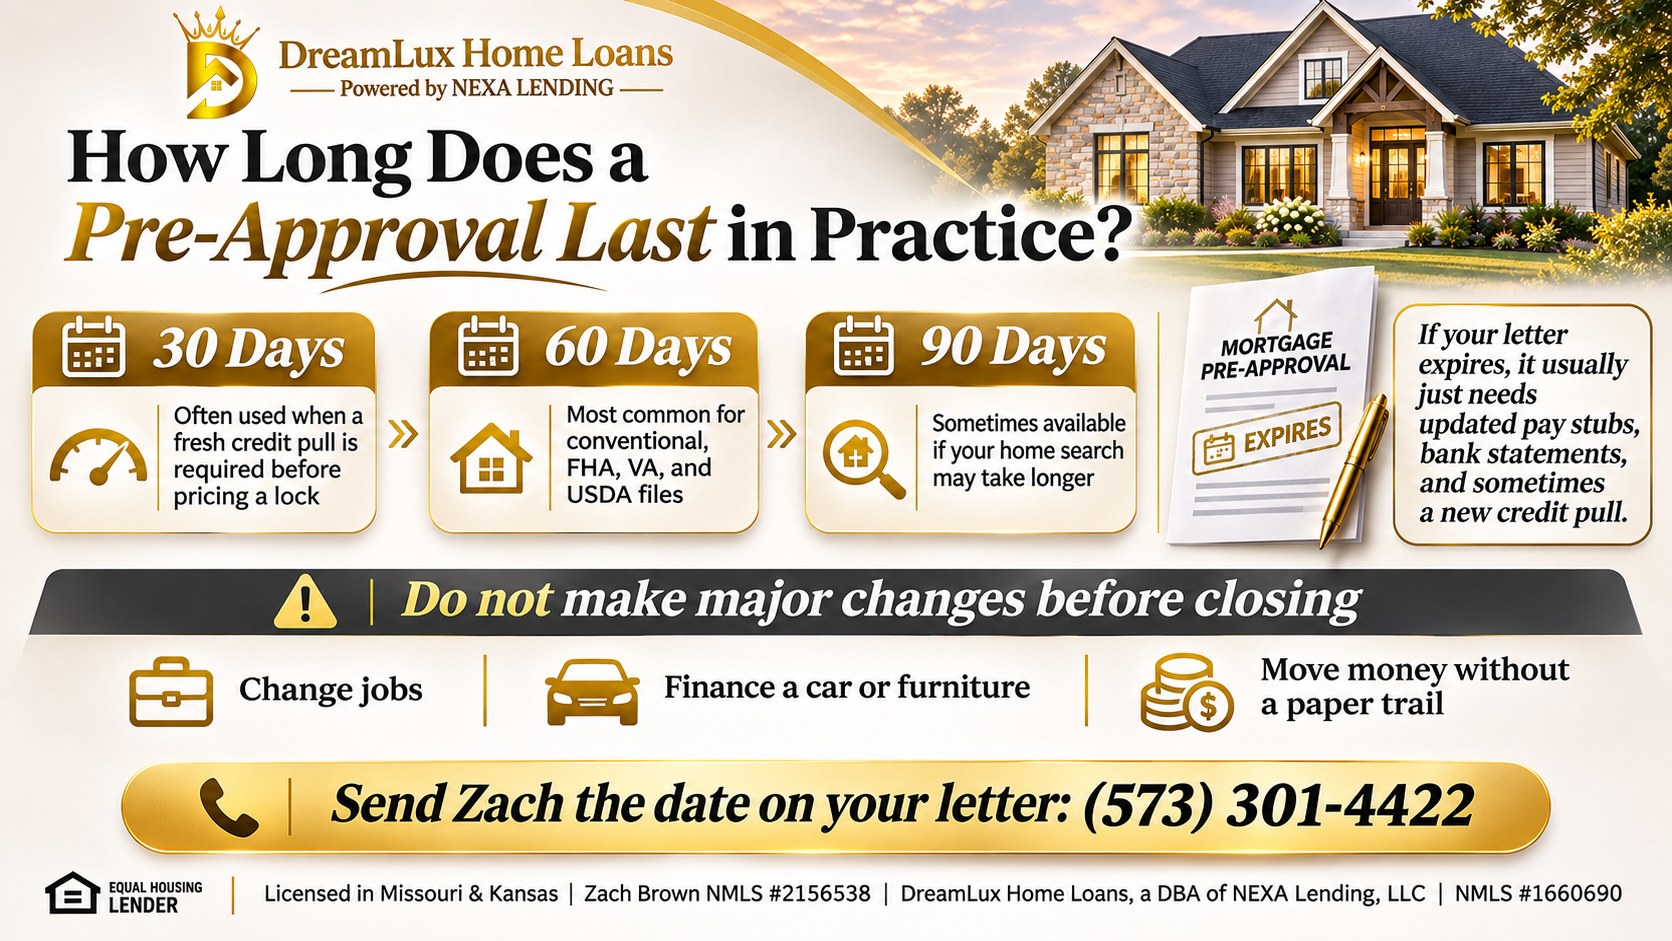
Most pre-approval letters in Missouri and Kansas are good for 30 to 90 days. Sixty days is the most common window; some lenders and credit unions issue 90-day letters, and a few investors shorten it to 30 so they can re-pull credit before they price a lock. The expiration date is printed on the letter itself, and it matters at offer time: a listing agent reading a letter that lapsed last week treats it as no financing at all.
How Long Does a Mortgage Pre-Approval Last in Practice?
- 30 days — common where the investor wants a fresh credit pull before pricing a lock.
- 60 days — the typical window for conventional, FHA, VA and USDA files.
- 90 days — usually a broker or credit union extension, and the one to ask for if your search may run past two months.
When a pre-approval is close to expiring, most lenders will re-issue it without a new application, provided your income, assets and credit still check out. Expect to send updated pay stubs and bank statements, and expect a second credit pull. A rate lock is a separate commitment with its own expiration and its own cost — never treat the pre-approval date as your lock date.
How Long Pre-Approval Takes to Issue
Turnaround depends on how fast documents arrive and how complex the file is. A straightforward W-2 borrower with complete paperwork is typically reviewed within a day or two; a self-employed borrower with multiple entities, rental properties or a jumbo loan takes longer because more documentation has to be read carefully.
Pre-approval letters usually carry an expiration, commonly somewhere between 30 and 90 days, and most lenders will refresh one with updated pay stubs and statements. If your rate lock matters to you, ask about the difference between a pre-approval letter and a locked rate — they are not the same commitment.
What Pre-Approval Does and Does Not Lock In
A pre-approval is a statement of creditworthiness, not a rate lock and not a guarantee. It can change if your financial picture changes before closing: a new car loan, a financed furniture purchase or a job change can alter the file. Once you are under contract, the loan still has to go through final underwriting on the specific property, including appraisal. Treat the pre-approval amount as a ceiling, not a target — buying below it usually means a more comfortable payment.
How to Compare Pre-Approval Offers From Multiple Lenders
This is where most buyers leave money on the table. Two lenders can approve you for the same loan amount at meaningfully different pricing, fees and program overlays. Compare, at minimum:
- Interest rate and any points quoted
- All lender fees, itemized on a Loan Estimate
- Whether the pre-approval was underwritten or automated
- Program fit: FHA, VA, USDA, conventional, jumbo or a specialty program
A broker works in the opposite direction from a single retail bank: instead of one rate sheet, one file is shopped across many wholesale lenders. DreamLux Home Loans works with access to 280+ lenders, which is the practical reason shopping a file matters. If you want the mechanics of that comparison, read mortgage broker vs. bank and our guide to conventional purchase financing in Missouri and Kansas.
Pre-Approval for Different Borrower Types
Program choice is decided at pre-approval, and the right program changes everything:
- FHA — lower credit and down payment thresholds, with mortgage insurance. See FHA mortgage loans.
- VA — no down payment for eligible service members, veterans and surviving spouses, including buyers near Fort Leonard Wood, Whiteman Air Force Base and the Truman VA community in Columbia.
- USDA — rural Missouri and Kansas properties, including many towns outside the metro corridors. See USDA loans.
- Physician loans — student debt treated differently and no PMI, for residents, fellows and attending physicians. See physician mortgage loans.
- Jumbo — above the conforming limit, common around the Lake of the Ozarks and higher-priced Kansas City suburbs.
- DSCR and investment property — qualification on rental income rather than your personal return.
Down payment assistance is also worth checking before you finalise a pre-approval, because it can change how much cash you need. Our down payment assistance page covers Missouri programs.
Frequently Asked Questions
How long is a mortgage pre-approval good for? Typically 30 to 90 days, with 60 days the most common in Missouri and Kansas. The expiration date is on the letter, and a lender can usually refresh it with updated documents before it lapses.
How long does a mortgage pre-approval last if I have not found a house yet? It still expires on the date printed on the letter. If your search is likely to run longer than two months, ask for a 90-day letter, and plan on a short refresh — new pay stubs, new statements and a second credit pull.
Does pre-approval hurt my credit score? A mortgage credit inquiry has a small effect, and multiple mortgage inquiries within a short window are generally treated as a single shopping event.
Can I get pre-approved before I have found a house? Yes, and you should. Pre-approval before touring keeps you from falling for a home you cannot finance.
Is pre-approval the same as approval? No. Final approval happens after underwriting reviews the specific property, the appraisal and the completed file.
Do I need pre-approval to make an offer in Missouri or Kansas? You do not strictly need it, but many sellers’ agents will not present an offer without it, and sellers routinely choose the offer with the strongest financing.
Ready to Get Pre-Approved?
DreamLux Home Loans is a licensed mortgage brokerage serving Missouri and Kansas, led by Senior Mortgage Loan Officer Zach Brown (NMLS #2156538). Whether you are buying in Columbia, Ashland, Jefferson City, Kansas City, St. Louis or at the Lake of the Ozarks, the first step is a pre-approval you can actually use — one that has been reviewed, priced across multiple lenders and matched to the right program for your situation. Start with the pre-approval checklist, then let us put your file in front of the lenders that fit it.








 Zach Brown | NMLS #2156538 | DreamLux Home Loans, a DBA of NEXA Lending, LLC | NMLS #1660690 | Equal Housing Lender | Licensed in Missouri & Kansas