Can a Streamline Rate and Term Refinance or VA IRRRL Lower Your Mortgage Payments in Missouri?
By Zach Brown, NMLS #2156538 | DreamLux Home Loans
A rate and term refinance may lower your Missouri mortgage payment by reducing your interest rate, extending your repayment term, or changing mortgage insurance costs. Whether it saves you money depends on closing costs, your new loan balance, and how long you expect to keep the loan.
If your mortgage payment feels heavier than it used to, start by finding out why. Then compare whether replacing your mortgage, addressing an existing expense, or keeping your current loan makes the most sense.
For homeowners in Columbia, Jefferson City, Ashland, Lake of the Ozarks, Kansas City, St. Louis, and surrounding Missouri communities, the goal is straightforward:
Know what you would pay, what you would owe, and what you would gain before making a change.
What Should You Know Before Refinancing?
· A lower payment does not always mean a lower-cost loan. Extending repayment can reduce your monthly obligation while increasing interest over time.
· Closing costs and your remaining balance matter. Compare both loans over the same period.
· Taxes and insurance can increase your payment independently of your interest rate. Check your statement before assuming you need a new mortgage.
· Your existing loan type helps determine your options. Conventional refinancing, FHA Streamline, and VA IRRRL have different requirements.
Already considering a refinance? Start your Missouri mortgage application with DreamLux Home Loans or book a conversation with Zach to discuss your next step.
What Is a Rate and Term Refinance?
A rate and term refinance replaces your existing mortgage with a new loan intended to change the interest rate, repayment term, or both, rather than withdraw substantial home equity.
The new mortgage pays off the existing loan. Your balance may increase if permitted closing costs are financed. Depending on the program, limited incidental cash back may be allowed.
The useful question is:
“Does the replacement loan improve the outcome I care about enough to justify its costs?”
That outcome could be:
· A lower required monthly payment.
· Less interest over your expected borrowing period.
· An earlier payoff date.
· More predictable payments.
· A change in mortgage insurance costs.
Choose the goal before choosing the loan.
Why Did Your Mortgage Payment Increase?
A higher payment on a fixed-rate mortgage does not necessarily mean your mortgage interest rate changed.
Your total payment may include principal, interest, property taxes, homeowners insurance, and mortgage insurance. An escrow shortage or the end of a temporary buydown can also affect the amount due. CFPB: Why mortgage payments change
| What changed? | What should you review first? |
| Property taxes or homeowners insurance increased | Your tax bill, insurance renewal, and escrow analysis |
| Your servicer is collecting an escrow shortage | The shortage amount and repayment schedule |
| An adjustable interest rate changed | Your adjustment notice and available fixed-rate alternatives |
| A temporary buydown ended | The payment schedule under your current loan |
| Mortgage insurance affects the payment | Whether cancellation or a different loan structure is available |
Refinancing does not eliminate property taxes or homeowners insurance. A lower principal-and-interest payment can be partly or entirely offset by increases in those expenses.
How Can Refinancing Lower Your Monthly Payment?
Refinancing changes the relationship between your interest rate, loan balance, and repayment schedule. Review those changes together.
A Lower Interest Rate
With the same balance and repayment period, a lower interest rate reduces the principal-and-interest payment.
Your actual offer depends on your qualifications, the property, the loan program, and market conditions. Compare personalized estimates rather than assuming an advertised rate applies to your situation.
A Longer Repayment Term
Spreading your balance over more years can reduce your required monthly payment.
The tradeoff is that you may make payments for longer and pay more total interest. If you have already paid down several years of your mortgage, compare the new loan against the years remaining on your current loan.
Ask to see a shorter-term alternative when available, especially if your goal is reducing total borrowing costs.
A Change in Mortgage Insurance
A refinance may change your mortgage insurance costs, but replacing the loan is not always necessary.
If you have conventional private mortgage insurance, ask your servicer whether cancellation is available under the applicable requirements. FHA mortgage insurance follows different rules. CFPB: Removing private mortgage insurance
How Do You Calculate Refinance Break-Even?
A simple cash-flow break-even estimate divides the refinance costs you need to recover by the monthly payment reduction.
Costs to recover ÷ monthly payment reduction = estimated break-even months
For an arithmetic illustration, suppose a homeowner pays $4,800 in transaction costs out of pocket and reduces comparable monthly loan payments by $200.
$4,800 ÷ $200 = 24 months
That estimates when payment reductions recover those upfront costs. This is an educational example, not a loan offer or a prediction of your savings.
Why Simple Break-Even Is Only Part of the Answer
Passing the cash-flow break-even point does not automatically mean you are financially ahead.
If the new loan extends your repayment schedule, you could make smaller payments while owing more when you sell. Financing closing costs can also increase your balance and interest paid.
Ask for a comparison at the same future date that includes:
· Payments made under each option.
· Upfront transaction costs and lender credits.
· Costs added to the new loan.
· Mortgage insurance paid.
· The remaining mortgage balance.
If you expect to sell in five years, compare both loans at five years. The balance you would need to pay off matters alongside the monthly savings.
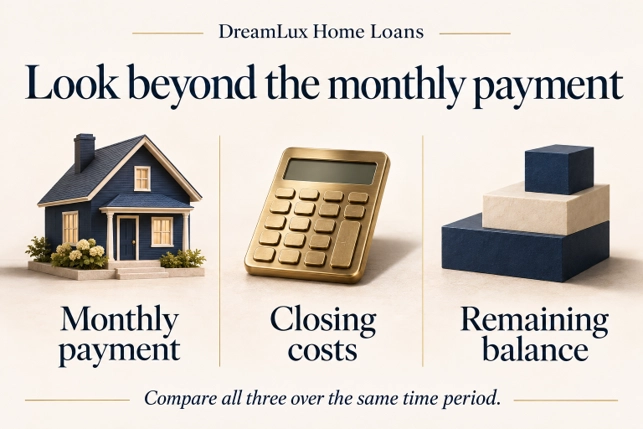
Look beyond the payment: compare transaction costs and remaining balances over the same period.
What Does Refinancing Cost in Missouri?
Refinance costs depend on the lender, loan program, property, and settlement services. An itemized Loan Estimate is more useful than a general statewide average.
Costs may include lender origination charges, discount points, an appraisal when required, title and settlement services, recording charges, and other applicable fees.
Prepaid interest and initial escrow funding can also affect the amount needed at closing. Separate those items from lender and settlement fees when evaluating the transaction.
Closing costs, cash to close, and your new loan amount are different figures. Review all three. CFPB: Loan Estimate explainer
Is a “No-Closing-Cost” Refinance Actually Free?
No. Costs may be covered through a lender credit associated with a higher interest rate, or financed into the loan balance when allowed.
Ask how each option changes your upfront cash, monthly payment, and cost over the period you expect to keep the loan. CFPB: Understanding loan costs
Can Working With a Mortgage Broker Help You Compare Costs?
An independent mortgage broker can help you compare available options from participating wholesale lenders, including differences in rates, fees, and loan structures.
Historical research supports the value of comparing lending channels. A 2024 Polygon Research study, supported by United Wholesale Mortgage and Willow Canyon Advisors, reported $10,662 in average lifetime savings for borrowers using independent mortgage brokers compared with nonbank retail lenders, based on its analysis of 2023 data.
The study also reported $13,432 in average savings per VA loan in its nonbank channel comparison. Research announcement and methodology
These are historical study averages. They are not current refinance quotes, Missouri-specific results, or guaranteed savings from DreamLux Home Loans.
The practical takeaway is to compare actual offers for your situation.
DreamLux Home Loans helps Missouri homeowners evaluate available mortgage options through NEXA Lending’s lender network. Ask how each option compares with keeping your current mortgage.
What Should Missouri Homeowners Compare Locally?
Your property’s location, actual expenses, and intended use help determine whether a refinance comparison is meaningful.
Columbia, Jefferson City, Ashland, and Nearby Mid-Missouri Communities
Start with your mortgage statement, property tax bill, insurance renewal, and escrow analysis.
These documents help distinguish a loan-payment issue from an increase in the ongoing costs of homeownership.
Kansas City, Lee’s Summit, Blue Springs, and Nearby Missouri Communities
Use your property’s actual Missouri address when requesting estimates.
Whether your home is in Kansas City, Lee’s Summit, Blue Springs, Independence, or another nearby Missouri community, the comparison should reflect your property’s taxes, insurance, settlement costs, and current mortgage terms.
Lake of the Ozarks and Nearby Communities
For properties in Lake Ozark, Osage Beach, Camdenton, and surrounding lake communities, explain whether the home is your primary residence, a second home, or an investment property.
Also identify whether it is a condominium. Property type and intended use can affect which financing options are available.
St. Louis and Surrounding Missouri Communities
Homeowners in St. Louis County, St. Charles County, Jefferson County, and nearby Missouri communities should compare actual property expenses and loan terms.
The strongest comparison is specific to your home, your current mortgage, and how long you expect to keep the replacement loan.
Should FHA and VA Borrowers Compare Streamline Refinancing?
Yes. If you already have an FHA or VA mortgage, ask whether the applicable streamline refinance is worth comparing with other available options.
FHA Streamline Refinance
An FHA Streamline refinance is intended for an existing FHA-insured mortgage and must meet applicable program requirements, including a net tangible benefit.
“Streamline” describes reduced documentation and underwriting requirements. It does not mean the transaction is free or that mortgage insurance disappears. HUD: FHA Streamline refinancing
VA Interest Rate Reduction Refinance Loan
A VA Interest Rate Reduction Refinance Loan, or IRRRL, refinances an existing VA-backed loan.
It may help eligible borrowers reduce payments or move from an adjustable interest rate to a fixed rate. Closing costs and any applicable funding fee still belong in the comparison. VA: IRRRL guidance
Compare DreamLux’s FHA Streamline and VA IRRRL options.
When Might Keeping Your Current Mortgage Be Better?
Keeping your current loan may be the stronger choice when refinancing costs outweigh the benefits.
That may happen when:
· You expect to sell or refinance again before recovering the costs.
· Your current mortgage is already competitively priced.
· Most of the payment reduction comes from extending repayment.
· Taxes or insurance caused the payment increase.
· PMI cancellation or another change to the existing loan could address your goal.
· The refinance leaves you owing substantially more at your expected sale date.
A useful review should include the “keep your current loan” option.
How Should You Compare Refinance Offers?
Request multiple Loan Estimates close together in time and compare equivalent structures. Match the loan type, term, loan amount, and rate-lock assumptions.
| Compare this | Why it matters |
| Interest rate and APR | Helps evaluate pricing; neither replaces a dollar comparison over your expected timeline |
| Points and lender credits | Shows the tradeoff between upfront cost and interest rate |
| Principal, interest, and mortgage insurance | Shows the comparable loan-payment obligation |
| Taxes and homeowners insurance | Prevents an understated escrow estimate from appearing to be loan savings |
| Cash to close and financed costs | Shows what you pay now and what increases your debt |
| Remaining balance at your expected exit date | Shows how much you would still owe under each option |
Ask for alternatives with different points or lender credits when available. Compare them over the shortest, longest, and most likely periods you expect to keep the loan. CFPB: Comparing points and lender credits
Want to explore the numbers first? Use all DreamLux mortgage tools, then bring your questions to the conversation.
Frequently Asked Questions About Refinancing in Missouri
How Much Does My Interest Rate Need to Drop Before Refinancing Is Worth It?
There is no single rate reduction that makes refinancing worthwhile for everyone. The answer depends on your balance, costs, new term, mortgage insurance, and how long you expect to keep the loan.
A smaller rate reduction may be useful with low costs, while a larger reduction can still disappoint if the fees are high or repayment is extended substantially. Compare the full transaction.
Can I Refinance Without Starting Over With a New 30-Year Loan?
You do not necessarily have to choose a new 30-year term. Ask which shorter repayment terms are available and how their payments fit your budget.
Compare the proposed payoff date with your existing payoff date. A lower rate and a longer repayment period solve different problems.
Can Closing Costs Be Added to My New Mortgage?
Some refinance programs allow eligible costs to be financed, subject to program and loan limits. Financing costs increases the amount borrowed and can add interest.
Rules differ by program. For example, HUD states that closing costs cannot be included in the new mortgage amount for an FHA Streamline refinance. Ask how your specific costs will be paid. HUD: FHA Streamline requirements
Can I Refinance If I Already Have an FHA or VA Loan?
You may have several options. Existing FHA borrowers can ask about FHA Streamline refinancing, while existing VA borrowers can ask about a VA IRRRL.
Eligibility and benefit requirements apply. Compare the payment, fees, mortgage insurance or funding fee where applicable, and remaining balance rather than assuming a streamlined process is automatically the best financial choice. HUD FHA guidance, VA IRRRL guidance
Can Refinancing Remove My Mortgage Insurance?
It may, depending on your current loan, equity, eligibility, and replacement loan. But refinancing is not always required to remove conventional PMI.
Ask your servicer about cancellation first, then compare that option with the costs of a new mortgage. FHA mortgage insurance is governed by different requirements. CFPB: PMI cancellation
Is Rate and Term Refinancing the Same as Cash-Out Refinancing?
No. Rate and term refinancing focuses on restructuring existing mortgage debt. Cash-out refinancing accesses equity through a new loan that also provides funds beyond paying off existing obligations and permitted costs.
If you want funds for renovations or debt consolidation, explain that goal before comparing programs. Using home equity to repay unsecured debt secures that debt with your home.
Should I Apply If I Am Not Sure Which Refinance Program Fits?
You do not need to select the program before reaching out. Start with your current loan information and what you want to accomplish.
If you are ready to begin the application process, start your DreamLux application. If you want to discuss the decision first, book a conversation with Zach.
What Should I Have Ready for a Refinance Conversation?
Have your latest mortgage statement available, along with your property city, current loan type if known, main goal, and estimated timeline for keeping the home or loan.
If you already received another lender’s Loan Estimate, have that available too. Use the approved secure process for documents and sensitive financial information.
Missouri Homeowners: Put Your Mortgage Numbers to Work
A better mortgage decision starts with a comparison built around your home, your loan, and your goals.
Connect with Zach Brown or Scott Wilson at DreamLux Home Loans to discuss whether a refinance fits your situation.
Whether you want to reduce your required payment, shorten repayment, compare FHA or VA options, or get a second opinion on an existing quote, ask for a written review showing:
· Your current mortgage alongside available alternatives.
· Estimated payments, closing costs, and lender credits.
· Any costs added to the new loan.
· A cash-flow break-even estimate.
· Remaining balances over the same comparison period.
You do not need to have every answer before getting started. Tell us what you want your mortgage to do better, and we can help you evaluate the next step.
Ready to Move Forward? Start Your Missouri Mortgage Application
Use our Bevri application to provide the information needed to begin reviewing your mortgage scenario.
Start My Missouri Mortgage Application
Have your property location, current mortgage information, and refinance goal available. An application begins the review process; approval and terms depend on the applicable requirements.
Want to Talk First? Reach Zach or Scott Directly
Zach Brown
Senior Mortgage Loan Officer & CEO
NMLS #2156538 | Licensed in Missouri & Kansas
Call Zach: 573-301-4422
Scott Wilson
Senior Mortgage Loan Officer
NMLS #2181239 | Licensed in Missouri
Call Scott: 714-713-1110
Prefer a scheduled conversation? Book a Refinance Review with Zach.
Explore the Mortgage Resources That Fit Your Next Step
· Use All DreamLux Mortgage Tools for calculators and comparisons.
· Explore Rate and Term Refinancing to learn about changing your rate or repayment term.
· Compare FHA Streamline and VA IRRRL Options if you already have an FHA or VA loan.
· Explore All Mortgage Loan Programs if your goals extend beyond refinancing.
Ready to find out what fits your Missouri home? Start your application, book a conversation, or call Zach or Scott today.
Zach Brown | NMLS #2156538 | Licensed in Missouri & Kansas. Scott Wilson | NMLS #2181239 | Licensed in Missouri. DreamLux Home Loans, a DBA of NEXA Lending, LLC | NMLS #1660690 | Equal Housing Lender.
Rates, fees, terms, program availability, and approval depend on borrower qualifications, property details, lender guidelines, and market conditions. Savings are not guaranteed. Historical study averages do not represent a personalized quote or guaranteed outcome. Educational examples are illustrative. This article is not a loan offer or commitment to lend. Calculator results and inquiries are not approvals. Use the approved secure application process for sensitive information and financial documents.








 Zach Brown | NMLS #2156538 | DreamLux Home Loans, a DBA of NEXA Lending, LLC | NMLS #1660690 | Equal Housing Lender | Licensed in Missouri & Kansas