Which Missouri Mortgage Fits Your Situation? Conventional, Jumbo, DSCR, VA, and Refinance Options
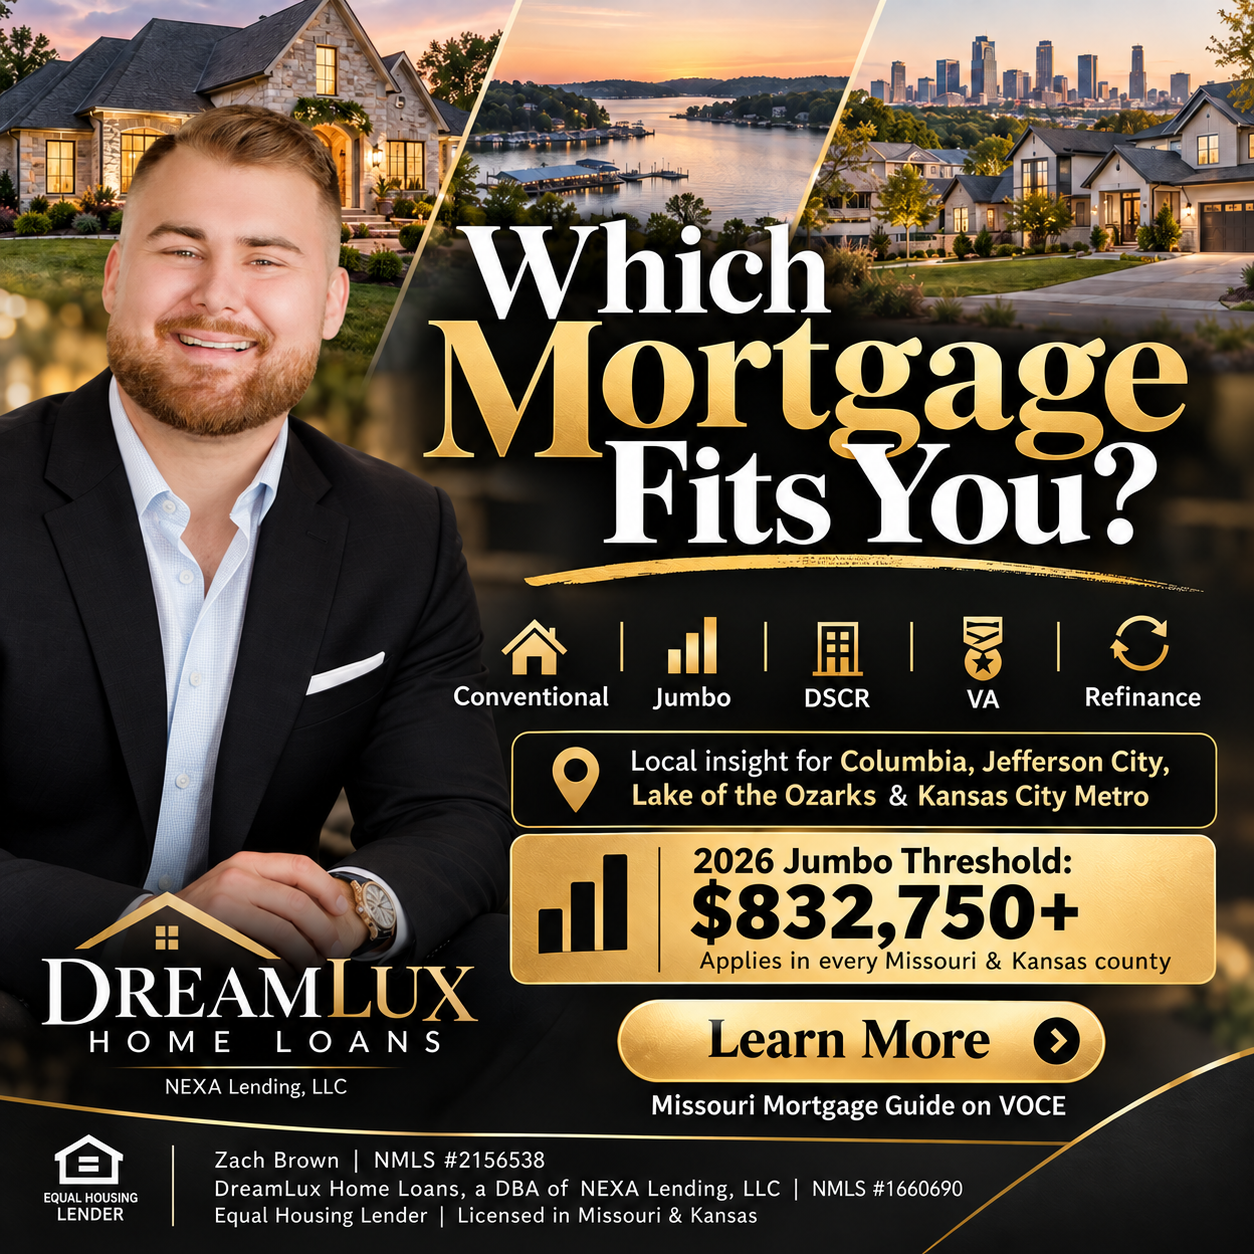
The right Missouri mortgage depends on three things: what you’re buying, how you earn your income, and whether you already own the home. A primary residence with W-2 income usually points to a conventional loan. A lakefront home or upper-bracket Kansas City property above the 2026 conforming limit of $832,750 is a jumbo loan. A rental you qualify on the property’s income, not your tax returns, is a DSCR loan. Eligible veterans and service members almost always start with VA. And if you already own, the question shifts to which refinance path fits: rate and term, FHA Streamline, or VA IRRRL.
Below is how I walk borrowers through each one, with the local wrinkles that matter in Mid-Missouri, at the Lake, and across the Kansas City metro on both sides of the state line. If you’d rather see every program side by side first, start with the Missouri and Kansas mortgage comparison page.
Key takeaways
- Primary residence with documented income: start with a conventional loan.
- Any loan above $832,750 in Missouri or Kansas is a jumbo loan in 2026, in every county.
- Rental property qualified on rent instead of tax returns: DSCR loan.
- Eligible veterans and service members: VA loan, almost every time.
- Already own: rate and term (conventional), FHA Streamline (FHA), or VA IRRRL (VA).
Want the short answer for your situation? I price one application across 280+ wholesale lenders and tell you plainly which program fits. No credit pull for a quote.
Zach Brown, NMLS #2156538. Licensed in Missouri and Kansas.
When does a conventional loan make sense in Columbia, Jefferson City, or Ashland?
A conventional loan is the default for most Mid-Missouri buyers with steady income and reasonable credit. It’s the loan I quote first for a buyer purchasing a primary residence in Columbia’s Old Southwest, a newer build in Ashland, or a home near the Capitol in Jefferson City.
Conventional works well when:
- You’re buying a primary residence, a second home, or a small investment property.
- Your income is documented (W-2, or two years of self-employment returns).
- You’d rather have mortgage insurance that can be removed once you build equity, instead of FHA insurance that stays for the life of the loan in most cases.
- You want flexibility on property type, including condos and multi-unit homes.
One thing Mid-Missouri buyers don’t always expect: conventional loans have low down payment options for first-time buyers, so “conventional” doesn’t automatically mean “big down payment.” Because I work as a wholesale broker, I price the same conventional file across many lenders, and the spread between the strongest and weakest quote on an identical borrower is often wider than people assume. The 30-year fixed is the workhorse, but a 15-year fixed is worth a look if you’re buying below your budget.
Local pages: Columbia, MO mortgage lender, Jefferson City, MO mortgage lender, Ashland, MO mortgage lender, and the Mid-MO pre-approval page.
When is a Missouri or Kansas mortgage considered jumbo?
In Missouri and Kansas, any loan amount above $832,750 is a jumbo loan in 2026. Neither state has a single high-cost county, so that line is the same whether you’re buying in Boone County, Camden County, Jackson County, or Johnson County, Kansas.
That number matters for two markets in particular:
- Lake of the Ozarks. Lakefront homes in Osage Beach, Sunrise Beach, the Village of Four Seasons, and the Gravois Arm near Laurie and Gravois Mills cross the jumbo line regularly, especially with a dock and a deep water lot. See Lake of the Ozarks jumbo and second home mortgages.
- Kansas City metro. Parkville, Leawood, Mission Hills, parts of Overland Park, and newer estate lots around Lee’s Summit and Raymore routinely price above the limit. See luxury home loans in Missouri.
Jumbo loans aren’t sold to Fannie Mae or Freddie Mac, so each lender sets its own rules on reserves, credit, and down payment. That’s where a broker earns their keep: one lender might want a large cash reserve while another will count retirement assets, and one might treat a Lake second home differently than a primary residence. I match the file to the lender whose rules fit the borrower instead of forcing the borrower to fit one bank’s box.
What is a DSCR loan, and does it work for a Lake of the Ozarks rental?
A DSCR loan (debt service coverage ratio) qualifies you on the property’s rental income compared to its mortgage payment, not on your personal tax returns or debt-to-income ratio. If the rent covers the payment, the property can qualify on its own.
DSCR fits investors who:
- Own a business or write off heavily, so tax returns understate real income.
- Already carry several financed properties and are hitting conventional limits.
- Want to close in an LLC (many DSCR lenders allow this; conventional generally does not).
At the Lake, the common question is whether short-term rental income counts. Some lenders will use projected short-term rental income for a property in Osage Beach or Camdenton, others only accept a long-term lease or a market rent appraisal. The answer depends on the lender, the property, and the local short-term rental rules, which vary by city and county around the Lake. Confirm the local ordinance before you write the offer, not after. Full detail on the DSCR loans for Lake of the Ozarks page, and if the unit is a condo, read the Lake of the Ozarks non-warrantable condo loan page first.
In Columbia, DSCR is how most investors finance student rentals near Mizzou. In Kansas City, it’s common for buyers picking up single-family rentals and small multifamily in Independence, Blue Springs, Grain Valley, and KCK, where entry prices still let the rent cover the payment. Self-employed buyers who want a primary residence instead of a rental should look at bank statement loans.
How does a VA loan work for veterans buying in Kansas City, Lee’s Summit, or Blue Springs?
If you’re an eligible veteran, active-duty service member, or surviving spouse, a VA loan is usually the first option to look at. There’s no down payment requirement for most borrowers with full entitlement, no monthly mortgage insurance, and the guaranty lets lenders offer terms that are hard to match elsewhere.
VA is a big part of my Kansas City business. Families stationed at Whiteman Air Force Base often buy along the Highway 50 corridor in Lee’s Summit and Blue Springs, and veterans transitioning out of service settle across Liberty, Parkville, Raymore, Olathe, and Overland Park. Because VA loans can be used across the state line, a Kansas City buyer can shop both Missouri and Kansas without changing loan programs. The Kansas City metro mortgage page covers the Missouri side and the Kansas mortgage lender page covers Johnson County.
Mid-Missouri veterans, including Fort Leonard Wood families relocating north, can start on the Columbia, Jefferson City, and Ashland VA loans page.
A few points that trip people up:
- VA doesn’t require a minimum credit score, but individual lenders set their own overlays. That’s another reason to shop lenders rather than accept the first “no.”
- Condos must be VA-approved. Check the list before you fall in love with a unit.
- The VA funding fee can be financed into the loan and is waived for veterans with a qualifying service-connected disability rating.
Already own a home? Which refinance is which: rate and term, FHA Streamline, or VA IRRRL
There are three refinance paths I see most often, and borrowers mix them up constantly. Rate and term is for conventional borrowers, FHA Streamline is for existing FHA loans, and VA IRRRL is for existing VA loans. None of the three allow cash out.
Rate and term refinance
You replace your existing loan with a new one to change the rate, the term, or both. No cash out beyond minor closing adjustments. This is the standard path for a conventional borrower in Columbia or Jefferson City who bought in a higher-rate period and wants to reset, or who wants to move from a 30-year to a shorter term. Details on the conventional refinance page.
FHA Streamline refinance
If your current loan is FHA, the Streamline lets you refinance with reduced documentation. In most cases there’s no new appraisal and no income re-verification. The catch is that the new loan has to produce a real benefit to you (a lower payment or a move from an adjustable rate to a fixed rate). You cannot take cash out through a Streamline. Background on the program is on the FHA loans page.
VA IRRRL (Interest Rate Reduction Refinance Loan)
This is the VA version of a Streamline, for borrowers already in a VA loan. Same idea: limited documentation, usually no appraisal, and the new loan must lower your rate or move you from adjustable to fixed. The funding fee on an IRRRL is reduced compared to a purchase, and it can be rolled into the loan. Full walkthrough on the VA IRRRL refinance page for Missouri and Kansas.
For all three, the honest test is simple: does the new loan put you in a better position after you account for closing costs and how long you plan to stay in the home? If it doesn’t, I’ll tell you to wait. I’d rather keep a borrower for their next transaction than push a refinance that doesn’t pencil. If you want equity out rather than a lower payment, that’s a different conversation, and a HELOC is often the cleaner tool. The Missouri and Kansas refinance overview lays all of it out.
How do you choose between all of these?
Start with the property and your income, not with the loan name.
| Your situation | Loan path |
|---|---|
| Primary residence, documented income | Conventional first, then compare against FHA if credit or down payment is tight |
| Loan amount above $832,750 anywhere in Missouri or Kansas | Jumbo |
| Rental property, qualifying on rent instead of tax returns | DSCR |
| Eligible veteran or service member | VA, almost every time |
| Already own with an FHA loan and rates have moved | FHA Streamline |
| Already own with a VA loan and rates have moved | VA IRRRL |
| Already own with a conventional loan | Rate and term refinance |
Then shop the lender, not just the program. As a wholesale broker licensed in Missouri and Kansas, I run one application across many lenders and let them compete for your file. That’s the part most borrowers never see, and it’s where the real difference between two offers usually comes from. The mortgage loan process page shows what that looks like step by step.
If you’re buying or refinancing in Columbia, Jefferson City, Ashland, anywhere around Lake of the Ozarks, or across the Kansas City metro, I’m glad to look at your situation and tell you plainly which path fits. Call or text (573) 301-4422, message me through the DreamLux Home Loans Google Business Profile, or visit dreamluxhomeloans.com.
Which loan fits where you’re buying?
Same rules, different local wrinkles. Here is the short version for each of the three markets I work most.
Columbia, Jefferson City, and Ashland
Mostly conventional and FHA purchases, a steady flow of first-time buyers near Mizzou and state offices, and physicians relocating for residency. Investors use DSCR for student rentals. Jumbo is rare outside a few Columbia neighborhoods.
Mid-Missouri mortgage hub · Physician loans · Get pre-approved
Lake of the Ozarks
Second homes and lakefront property drive jumbo volume, and short-term rental investors drive DSCR. Condos on the Lake often need a non-warrantable condo program, so ask before you write the offer.
Lake jumbo and second home · Lake DSCR · Non-warrantable condos
Kansas City Metro, Missouri and Kansas
VA is a large share of the business along the Highway 50 corridor from Whiteman. Conventional dominates the Johnson County suburbs, jumbo shows up in Leawood, Mission Hills, and Parkville, and DSCR is common for rentals in Independence and KCK.
Kansas City metro hub · Lee’s Summit and Blue Springs · Kansas side
Already know which program you need? Send the basics and I will come back with lender options, not a sales pitch.
Frequently asked questions
- Is a jumbo loan harder to qualify for than a conventional loan?
- Usually the credit, reserve, and documentation requirements are stricter, but they vary lender to lender because jumbo loans aren’t sold to Fannie Mae or Freddie Mac. A broker can place the file with the lender whose rules fit you.
- Can I use a DSCR loan for a short-term rental at Lake of the Ozarks?
- Some lenders will, using projected short-term rental income or a market rent appraisal. Others require a long-term lease. Local short-term rental ordinances around the Lake also affect eligibility, so confirm the rules for the specific city or county before you make an offer.
- Can a VA loan be used in both Missouri and Kansas?
- Yes. VA loans are federal, so a Kansas City buyer can shop in Lee’s Summit or Overland Park with the same program and the same entitlement.
- What’s the difference between an FHA Streamline and a VA IRRRL?
- Both are reduced-documentation refinances for borrowers already in that loan type, and both generally skip the appraisal. FHA Streamline is for existing FHA loans; IRRRL is for existing VA loans. Neither allows cash out.
- Does a rate and term refinance let me take cash out?
- No. Rate and term changes your rate or loan term only. If you want to pull equity, that’s a cash-out refinance or a HELOC, each with its own rules.
- My bank denied me in Columbia. What are my options?
- A denial from one bank is one lender’s rulebook, not a verdict. As a wholesale broker I can place the same file with a lender whose guidelines fit your credit, income type, or property. Common fixes: FHA instead of conventional, a bank statement loan for self-employed income, or a DSCR loan if the property is a rental. Bring the denial letter and I will tell you which path is realistic.
- I am self-employed in Kansas City. Can I still buy a primary residence?
- Yes. If two years of tax returns support the income, conventional works. If write-offs make your returns understate what you earn, a bank statement loan qualifies you on 12 or 24 months of deposits instead. DSCR is only for rentals, not the home you live in.
- I am relocating to Whiteman Air Force Base. When should I get pre-approved?
- As soon as you have orders. A VA pre-approval lets you shop Lee’s Summit, Blue Springs, Grain Valley, and Warrensburg with confidence, and your Certificate of Eligibility can be pulled during the application. Buying before you arrive is common, and the appraisal and closing can happen while you are still at your current station.
- My credit is in the mid-600s. Can I buy at Lake of the Ozarks?
- Usually. FHA and VA are more forgiving on credit than conventional, and some lenders in my network go lower than the big banks on jumbo and DSCR files. The property type matters as much as the score: a lakefront condo may need a non-warrantable program regardless of credit.
Useful mortgage tools for Missouri and Kansas buyers and owners
Everything here is free, and none of it requires a hard credit pull. Start with whichever matches where you are.
Search Missouri and Kansas homes
Get the pre-approval before the showing
Browse active listings across both states and save searches. The same soft-pull pre-approval carries to any of them.
Browse active listings and get introduced to an agent
Search every active Missouri and Kansas listing through our MLS home search and save the ones you like. Need an agent? We introduce you to a licensed partner agent in your market at no cost to you. Zach handles financing only; listing-side and negotiation work stays with the licensed agent.
Send me your loan estimate. I will read it line by line.
Already have a quote from a bank, a credit union, or an online lender? Send the three-page Loan Estimate and I will walk you through what it actually says, where the cost lives, and whether our lender panel would price the same file differently. No credit pull, no application, no obligation.
What gets checked
- Section A origination charges
- Section C services you can shop for
- Lender credits and discount points
- Page 3 “In 5 Years” and Total Interest Percentage
What it is not
- Not a promise to beat it
- Not a credit pull
- Not a comparison of prepaids and escrows
- Not a rate quote

For sale by owner
Buying or selling a FSBO home in Missouri or Kansas?
Zach Brown is a preferred mortgage partner for FSBO.com in Missouri and Kansas. Sellers list through our partner link; buyers show up with an underwritten pre-approval that a for-sale-by-owner seller can trust without an agent vetting it for them.
If you are selling
List on FSBO.com through our invite link and get $99 off the Plus or MLS plan. Your listing reaches the same buyer sites an agent’s listing does, and buyers who call us get pre-approved before they tour your house.
If you are buying
A FSBO seller has no agent telling them your financing is real. Our pre-approval letter is underwritten first, names the program, and comes with a broker the seller can call. That is what gets a FSBO offer accepted.
Affiliated Business Arrangement Disclosure. DreamLux Home Loans is a DBA of NEXA Lending, LLC. NEXA Lending, LLC and FSBO.com share common ownership. Because of that relationship, referrals between the two may provide a financial or other benefit. You are not required to use FSBO.com to obtain mortgage financing from DreamLux Home Loans, and you are not required to use DreamLux Home Loans to list a property on FSBO.com.

Wholesale pricing
DreamLux Home Loans wholesale mortgage rate quotes
Whichever program fits, the price comes from which lender takes the file, the credit tier, and the points or credit you choose. Request a quote (no SSN, no credit pull) and I show the same loan three ways.
Rates subject to change. Not a commitment to lend. Quotes depend on credit, loan-to-value, property, occupancy, program, and lock period, and are provided by a licensed loan officer.
About the author
Also published on VOCE. Read, ask a question, or follow Zach there:
Missouri Mortgage Guide: Conventional, Jumbo, DSCR & VA
Find the right Missouri or Kansas mortgage for your situation.
What Missouri and Kansas homebuyers say
Reviews are collected and verified by Experience.com after closing and published as written. This widget shows 4- and 5-star reviews. The full rating breakdown and every review, including any lower ratings, are on my Experience.com profile.
Individual results vary. Loan approval depends on credit, income, assets, property, and program guidelines. Reviews reflect the experience of the borrower named and are not a guarantee of any outcome.
Official entity reference
Verify DreamLux Home Loans Facts
Review official details for DreamLux Home Loans, Zach Brown NMLS #2156538, NEXA Lending, Missouri and Kansas mortgage services, loan programs, service areas, and contact information.